Espartaco

“Is that to say we are against Free Trade? No, we are for Free Trade, because by Free Trade all economical laws, with their most astounding contradictions, will act upon a larger scale, upon the territory of the whole earth; and because from the uniting of all these contradictions in a single group, where they will stand face to face, will result the struggle which will itself eventuate in the emancipation of the proletariat.”

Karl Heinrich Marx · Marx-Engels Collected Works, Vol. VI, p. 290

27,395 views since December 2020

27,395 visitas desde diciembre de 2020

EnglishEspañol

Category: Political Economy

  • Sectorial Exclusion Criteria in the Marxist Analysis of the Average Rate of Profit: The United States Case (1960-2020)

    Sectorial Exclusion Criteria in the Marxist Analysis of the Average Rate of Profit: The United States Case (1960-2020)

    LISTEN TO THIS POST AS A PODCAST

    What Counts as “The Economy”? A Marxist Framework for Measuring Capitalism’s Rate of Profit
    Marxist Economics  ·  Econometrics  ·  Political Economy

    What Counts as “The Economy”?
    A Marxist Framework for Measuring Capitalism’s Rate of Profit

    Before asking whether the rate of profit falls, we first have to decide whose profit rate we are measuring — and which economic activities actually belong in the theoretical object under study.

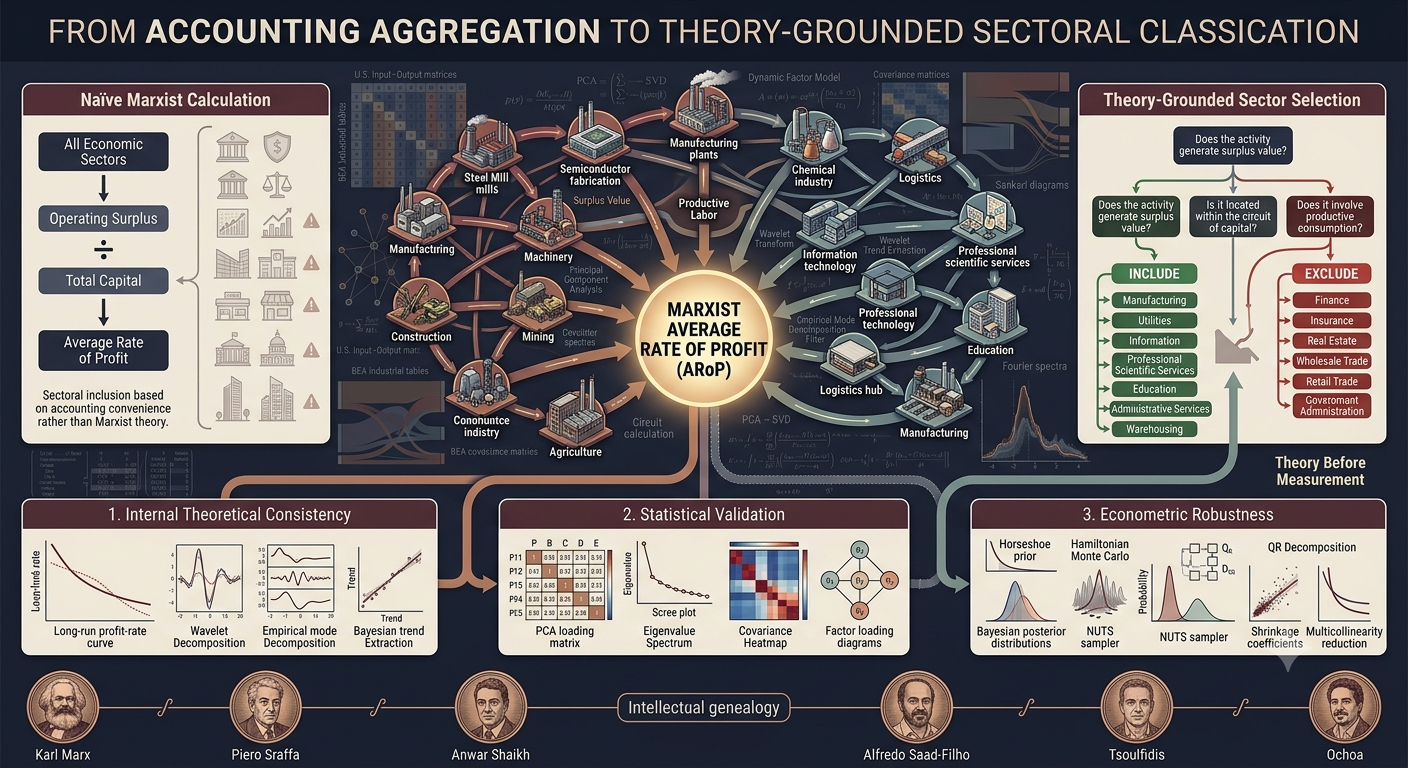
    Since the empirical work of Anwar Shaikh and Edgardo Ochoa in the 1980s, researchers in Marxian economics have repeatedly tried to measure one of Marx’s most discussed propositions: the long-run tendency of the average rate of profit to fall. Yet underneath the familiar formula lies a prior problem that can materially change the result: which sectors of the economy should enter the calculation in the first place?

    Manufacturing? Almost certainly. Finance? Perhaps not. Retail trade? Transportation? Government? Education? Warehousing? Modern national accounts combine activities that occupy very different positions in Marx’s theory of value and capital.

    José Mauricio Gómez Julián’s paper argues that this cannot be treated as an arbitrary data-cleaning choice. If the quantity being estimated is specifically a Marxian average rate of profit of productive capital, then the sectoral boundary should itself follow from the theory whose proposition is being measured.

    ◆

    The Measurement Problem Comes Before the Formula

    The paper calls the conventional alternative the naive Marxist calculation (nMc): constructing a profit-rate measure from broad national-accounting aggregates without first making a theoretically explicit distinction between productive and unproductive sectors.

    The criticism is not that the arithmetic is incorrect. It is that an aggregate combining activities that create surplus value with activities that mainly circulate, redistribute, realize, or consume surplus may fail to correspond closely to the Marxian theoretical object being discussed.

    The key point: a profit-rate series is produced not only by a formula, but also by the population of sectors placed inside that formula. Change the population and the historical trajectory can change with it.

    Three Pillars: The Theoretical Logic Behind the Criteria

    The paper’s framework rests on three interlocking questions drawn from Marx’s political economy. They are meant to determine whether an activity belongs within the productive capital whose profitability is being measured.

    1. Productive vs. Unproductive Labor

    In Marxian theory, “productive” is a technical category, not a synonym for socially useful. Productive labor is labor employed within the capitalist production process that produces value and surplus value. An activity can be necessary, socially useful, and remunerated while still being classified as unproductive in this specific theoretical sense.

    Pure circulation activities are the clearest case. Buying, selling, bookkeeping, and related operations may be indispensable to capitalist commerce, but if their function is only to change the form or ownership of already-produced value, they do not thereby create new value.

    The functions of capital in circulation do not, by themselves, create value or surplus value.

    — Summary of Marx’s argument in Capital, Volume II

    2. Location in the Circuit of Capital

    Capital moves through production and circulation rather than remaining in one form. The paper therefore asks whether an activity belongs to the productive reproduction of capital or primarily to circulation, redistribution, or a different institutional logic.

    This distinction matters because not every activity carried out between production and final sale is automatically unproductive. Transportation is the classic case: changing a commodity’s location can itself constitute a necessary material transformation and can therefore add value.

    3. Relationship with Surplus Value

    The final question is whether an activity directly produces surplus value or constitutes an indispensable material condition for its production. Activities that merely redistribute or realize value are treated differently from activities whose labor participates in the productive process itself.

    The Service-Sector Problem

    One of the paper’s strongest theoretical points is that “services” cannot be treated as a single Marxian category. Modern national accounts combine radically different activities under that label.

    Drawing partly on the functional approach discussed by Tregenna, the paper distinguishes among services that:

    • directly produce surplus value;
    • facilitate or materially condition surplus-value production elsewhere;
    • remain outside the productive circuit of capital.

    Hybrid sectors therefore have to be examined internally rather than included or excluded simply because a statistical agency labels them “services.”

    ◆

    Applying the Criteria: What’s In, What’s Out

    Because BEA industry classifications change over time, the paper first consolidates the U.S. data into a common system of 47 economic activities for 1960–2020. The theoretical criteria are then applied to each activity.

    Included — Productive

    • Farms
    • Forestry, fishing & related activities
    • Oil & gas extraction
    • Mining and mining support
    • Utilities
    • Construction
    • Manufacturing industries
    • Transportation
    • Warehousing & storage
    • Information
    • Professional, scientific & technical services
    • Management of companies & enterprises
    • Administrative & waste management services
    • Educational services
    • Arts, entertainment & recreation
    • Accommodation
    • Food services & drinking places
    • Other services except government

    Excluded — Non-Productive

    • Wholesale trade
    • Retail trade
    • Finance & insurance
    • Real estate
    • Rental & leasing services
    • Health care & social assistance
    • Federal general government
    • Federal government enterprises
    • State & local general government
    • State & local government enterprises

    The Borderline Cases

    Warehousing and storage is included where preservation of a commodity’s physical properties constitutes a material continuation of the productive process. The argument is therefore stronger than the simple claim that storage is commercially useful.

    Educational services is a much more difficult case. The statistical category mixes private, public, nonprofit, productive, and potentially unproductive activities. The paper nevertheless includes it because reproduction of skilled labor power is treated as a necessary condition of production in an advanced industrial economy.

    Administrative and waste-management services is also heterogeneous. Its inclusion is explicitly conditional: the paper argues that a sufficiently large share of these activities is connected with productive enterprises and supports their production process. The same classification need not automatically hold in every country or period.

    Information is included because the modern category encompasses software, informational and cultural products, technical infrastructure, data processing, hosting, and related forms of production. An apparently “immaterial” output is therefore not treated as automatically unproductive.

    ◆

    How the Profit Rate Is Constructed

    The empirical calculation combines sectoral surplus with the capital advanced and then aggregates the selected productive sectors. In schematic form:

    \[ r_t = \sum_{i\in P} w_{it} \left( \frac{s_{it}}{c_{it}+v_{it}} \right) \]

    Here \(P\) is the set of included sectors, \(s_{it}\) is sectoral surplus, \(c_{it}\) constant capital, \(v_{it}\) variable capital, and \(w_{it}\) the corresponding sectoral weight.

    The construction is subject to an important data limitation: sufficiently disaggregated fixed-capital and intermediate-input data are not directly available for every sector throughout the full period. The paper therefore uses proportional-disaggregation assumptions inherited from earlier empirical work, including Ochoa’s methodology. These reconstructed magnitudes should not be mistaken for fully observed sectoral capital stocks.

    ◆

    Internal Consistency: Does the Theoretically Constructed Rate Fall?

    The paper distinguishes carefully between internal theoretical consistency and the much stronger claim that an entire theory has been proven true.

    Marx’s theoretical system contains a proposition concerning a long-run tendency of the average rate of profit to fall. The first empirical question is therefore whether the series generated by the proposed sectoral criteria behaves consistently with that proposition.

    Three different trend-extraction methods are used:

    • Less-asymmetric Daubechies wavelets, with eight vanishing moments and decomposition depth \(J=4\);
    • Empirical Mode Decomposition (EMD), a data-adaptive and nonparametric decomposition;
    • an embedded Hodrick–Prescott trend within a Bayesian unobserved-components model estimated through Gibbs sampling.

    Periodogram and short-time Fourier analysis are also used beforehand to examine the spectral structure and support the use of additive rather than multiplicative decomposition.

    Under the theoretically selected sector set, all three methods produce a declining long-run trend in the net average rate of profit over 1960–2020. The result is not a monotonic straight line: cyclical recoveries and large shocks remain visible around the secular movement.

    What Do the Unit-Root Tests Say?

    The evidence is more mixed than the original blog version suggested. The paper evaluates 17 specifications across four test families: Augmented Dickey–Fuller, Elliott–Rothenberg–Stock, KPSS, and Phillips–Perron.

    ADF and PP frequently fail to reject the unit-root null; some ERS specifications do reject it; and KPSS generally does not reject stationarity, particularly stationarity around a deterministic trend.

    The appropriate conclusion is therefore not that every test rejects a unit root. Read jointly with the Wavelet, EMD, and Bayesian UCM-HP evidence, the paper interprets the results as being more consistent with a deterministic, potentially nonlinear trend.

    ◆

    Three Econometric Cross-Checks

    The paper then asks whether alternative, statistically generated sectoral cores lead to a substantially different conclusion. Three methods are used: Principal Component Analysis, Regularized Horseshoe Regression, and a Dynamic Factor Model.

    A crucial clarification: these procedures do not receive the theoretical productive/unproductive labels as the answers they are supposed to reproduce. But they should not be described as completely theory-free “blind tests” either. In particular, the RHR and DFM specifications use variables chosen because of their Marxian interpretation.

    The algorithms are statistical; the research design in which they operate is not theoretically neutral.

    Test 1: Principal Component Analysis

    The PCA is implemented through Singular Value Decomposition. Seven principal components are retained according to the eigenvalue and explained-variance criteria described in the paper.

    Rather than imposing an arbitrary loading cutoff, probability distributions are fitted to sectoral contribution measures, and the upper tail is used to identify unusually large contributions. Operationally, the paper selects the top decile within each retained component.

    The union of these selections leaves 26 of the 47 activities. A post-hoc check of the 21 discarded sectors finds that none reaches an eigenvalue-equivalent contribution above one in the first five principal dimensions; the largest reported value is approximately 0.77 for health care.

    PC1 deserves a nuance. Although its loadings are visibly associated with corporate and financial activities, the later interpretation notes that contributions to PC1 are relatively uniform and therefore treats it largely as an aggregate size or inertia component rather than the most discriminating structural factor.

    Test 2: Regularized Horseshoe Regression

    The RHR exercise is deliberately specified in a way connected with the labor theory of value: Total Gross Operating Surplus is modeled using sectoral Variable Capital as predictors.

    The model uses a Regularized Horseshoe prior with an expectation of roughly 16 relevant sectors and employs QR reparameterization in Stan to improve computation under extreme multicollinearity.

    This multicollinearity is not a minor inconvenience. With 61 annual observations and 47 strongly interdependent predictors, the posterior coefficients are heavily shrunk and no credible claim of conventional individual-sector significance can be sustained.

    The robust result is therefore not a list of “significant causal sectors,” but the predictive ordering produced by projpred: which variables enter fastest as predictive performance improves.

    The top 15 sectors are:

    1. Retail Trade
    2. Textile Mills & Textile Products
    3. Fabricated Metal Products
    4. Administrative & Waste Management Services
    5. Miscellaneous Manufacturing
    6. Construction
    7. Educational Services
    8. Electrical Equipment, Appliances & Components
    9. Nonmetallic Mineral Products
    10. Support Activities for Mining
    11. Printing & Related Support Activities
    12. Primary Metals
    13. Food Services & Drinking Places
    14. State & Local General Government
    15. Transportation

    Test 3: Dynamic Factor Model

    The DFM starts from the 47 sectoral series after logarithmic differencing and standardization. The Bai–Ng IC2 criterion selects the number of latent factors, while AIC selects the VAR lag order.

    The resulting model contains two factors and one VAR lag. Its estimated transition matrix is:

    \[ A = \begin{pmatrix} 0.3329 & 0.3253 \\ 0.1680 & 0.9129 \end{pmatrix} \]

    The first diagonal coefficient corresponds to a relatively low-persistence component; the second is highly persistent and is interpreted as reflecting longer-run accumulation dynamics. Together, the two factors explain approximately 34.01% of total variation in the standardized, differenced sectoral panel.

    Validation goes well beyond ranking factor loadings. The procedure combines multi-horizon prediction, Elastic Net, stability selection, synchronized block bootstrap, Partial \(R^2\), loading–sensitivity interactions, and a Full-Robust Thresholding procedure whose null distributions correct for factor indeterminacy through Procrustes/Hungarian alignment.

    Under the paper’s strict four-part predictive screen, no individual sector survives as a stable unilateral predictor of the aggregate profit rate. This is interpreted as consistent with a systemic rather than single-sector mechanism.

    At the same time, the structural synchronization weights are highly unequal. The empirical core is led by Real Estate, State & Local General Government, Federal General Government, Retail Trade, and Food Services, with Utilities and Chemical Products among the industrial baseline.

    ◆

    The Key Revelation: Theoretical and Statistical Cores Diverge

    Where Theory and Data Overlap

    Manufacturing repeatedly appears among the statistically important sectors and is unambiguously included by the theoretical criteria.

    Construction, transportation, utilities, educational services, and administrative services also appear with substantial weight under one or more econometric approaches while belonging to the theoretically selected productive set.

    This overlap shows that the theoretical and statistical classifications are not unrelated — but it does not establish that they are measuring exactly the same concept.

    Where Theory and Data Diverge

    Real Estate carries the highest structural weight in the reported DFM ranking, despite being theoretically excluded.

    Federal and state/local government also receive high DFM weights while remaining outside the paper’s theoretical productive-capital boundary.

    Retail Trade ranks first under the RHR predictive ordering and also appears prominently in the DFM, yet is excluded theoretically as an activity of circulation.

    Finance is prominent in the PCA structure, while health care records the largest post-hoc PCA contribution among the sectors discarded by that selection.

    The statistical result is therefore a divergence between the sectoral core defined by Marxian value theory and the sectors that dominate covariance, prediction, or synchronization in the observed national accounts.

    The paper interprets this through Marx’s distinction between essence and phenomenal appearance. Activities treated as unproductive in value-theoretic terms can still exert enormous influence over the observable movement of contemporary aggregate profitability.

    This distinction is important: the econometrics establishes different statistical rankings and structures. The claim that this difference should be understood as an essence/appearance relation is the paper’s Marxian theoretical interpretation of those empirical results.

    ◆

    Does the Rate of Profit Fall?

    The paper’s strongest robustness exercise repeats the long-run trend analysis using four different sectoral selections: the theoretical criterion, PCA, Regularized Horseshoe, and DFM. Each is then passed through the three trend-extraction methods.

    • Theoretical sectors + Wavelet → declining
    • Theoretical sectors + EMD → declining
    • Theoretical sectors + HP → declining
    • PCA sectors + Wavelet → declining
    • PCA sectors + EMD → declining
    • PCA sectors + HP → declining
    • RHR sectors + Wavelet → declining
    • RHR sectors + EMD → declining
    • RHR sectors + HP → declining
    • DFM sectors + Wavelet → declining
    • DFM sectors + EMD → declining
    • DFM sectors + HP → flat/rising exception

    In other words, the qualitative declining tendency survives 11 of the 12 combinations.

    The DFM–HP exception is not discarded. The paper relates it to the interaction between the state-space HP specification and a DFM sectoral core heavily influenced by real estate and government, whose accounting dynamics may differ from those of productive capital.

    EMD yields the most pronounced declining tendency across the comparisons, which the paper associates with its adaptive, nonparametric character.

    ◆

    What the Evidence Does — and Does Not — Establish

    The first contribution is methodological standardization. The paper turns sector selection from a largely implicit convention into an explicit and reproducible theoretical procedure.

    Second, the theoretically constructed profit-rate series displays the long-run decline predicted by the surrounding Marxian theoretical system. In the terminology of the paper, this supports the internal consistency of the proposed classification.

    Third, alternative statistically generated sectoral selections also produce a declining long-run rate in almost every methodological combination. That makes it harder to attribute the qualitative result solely to one hand-picked list of industries.

    But none of this logically proves the Marxian theory of value as a whole, nor does one U.S. study establish that the tendency must hold across every country and historical period. The paper explicitly distinguishes consistency within a theoretical system from the much stronger question of the theory’s overall validity.

    What Still Needs to Be Tested

    The empirical exercise covers one country and one historical period: the United States from 1960 to 2020. The natural next step is replication across other economies, periods, and institutional structures.

    Some theoretical classifications are necessarily conditional because broad BEA sectors contain heterogeneous activities. Education and administrative services are particularly clear examples where finer disaggregation could modify the classification.

    The RHR exercise is also operating in a difficult \(N=61,\;P=47\) environment with extreme multicollinearity. Its defensible output is predictive ordering, not a set of identified causal effects for individual sectors.

    Finally, PCA and DFM answer questions about covariance, synchronization, and statistical structure that are not identical to the Marxian theoretical question of where surplus value is produced. Their value lies in comparing those distinct objects rather than pretending that they are interchangeable.

    The most defensible bottom line: the paper does substantially more than show another declining profit-rate graph. It specifies what should count as productive capital, makes that rule reproducible, checks its compatibility with the broader theoretical system, and then tests whether the qualitative result survives very different statistical constructions of the economy.

    The answer is strikingly robust: in the U.S. data examined here, the long-run decline survives almost every combination. But the paper is better read as a first systematic piece of a larger empirical program than as the final word on the law itself.
  • Quantitative Theory of Money or Prices? A Historical, Theoretical, and Econometric Analysis

    Quantitative Theory of Money or Prices? A Historical, Theoretical, and Econometric Analysis

    LISTEN TO THIS POST AS A PODCAST

    Does Money Drive Prices, or Do Prices Drive Money?
    Econometrics · Monetary Theory · Machine Learning · Political Economy

    Does Money Drive Prices, or Do Prices Drive Money?

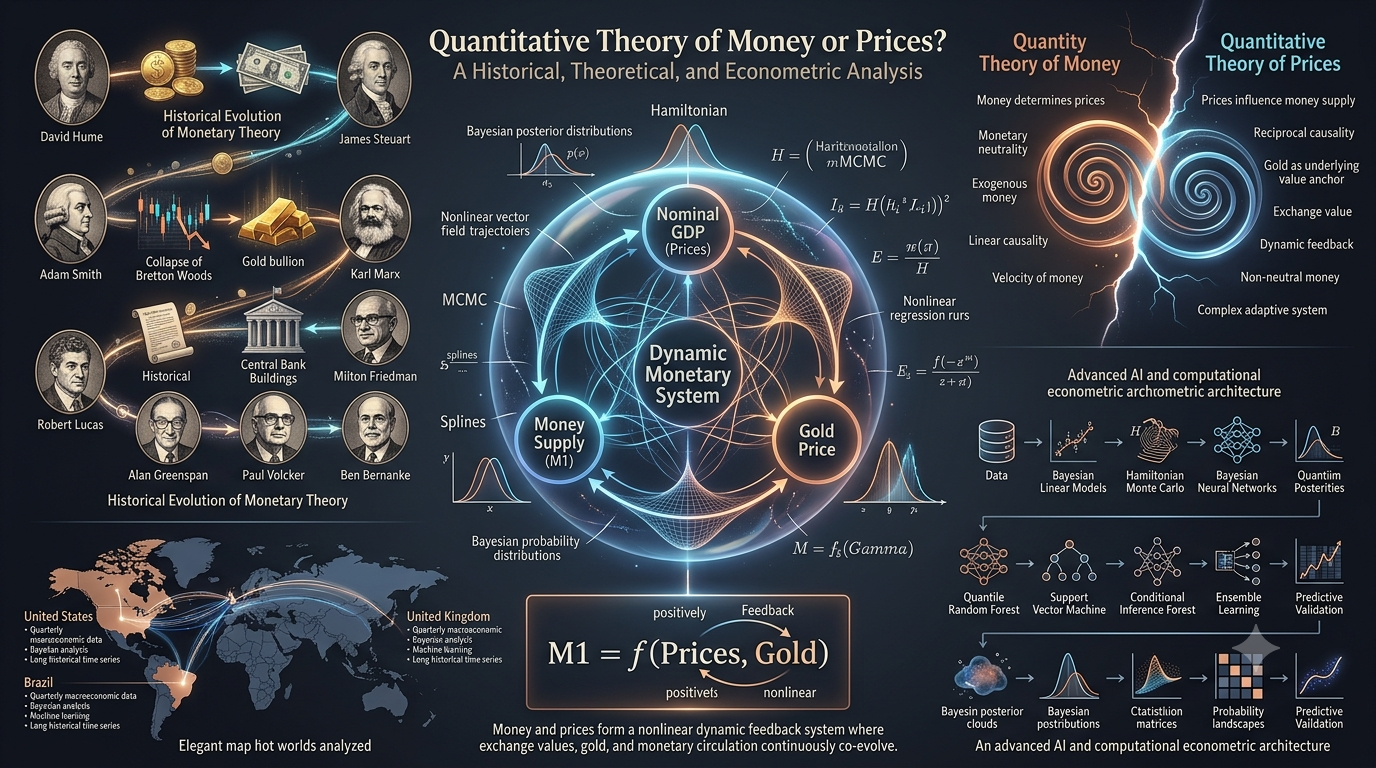
    Hume versus Marx, four countries, up to six decades of quarterly data, Bayesian statistics and machine learning — a modern empirical test of competing theories about the relation between money, prices and gold

    What you will find in this post
    1. The dispute between Hume and Marx — what each theory says is subordinate to what
    2. Marx’s critique of the Quantity Theory — four arguments and two empirical corollaries
    3. Gold after Bretton Woods — the paper’s case for a continuing indirect monetary role
    4. The mathematical model — the proposed relation among M1, nominal GDP and gold
    5. The econometric strategy — Bayesian regression, RESET, BGLMs, machine learning and ensembles
    6. Country-by-country evidence — United States, Canada, United Kingdom and Brazil
    7. Feedback and monetary non-neutrality — what the paper concludes and what the models directly establish
    8. Policy implications and open questions — where the argument leads and where research must continue
    · · ·

    1. The Old Dispute: Which Variable Is Subordinate?

    Few questions in monetary economics sound simpler than this one: does a larger quantity of money raise prices, or does the quantity of money required in circulation adjust to values and prices generated elsewhere in the economy? The difference is not semantic. It concerns the direction of determination between the monetary sphere and the production-and-exchange process that money expresses.

    David Hume is the historical point of departure of the paper. His monetary writings became an important ancestor of later versions of the Quantity Theory of Money, including the tradition associated with Milton Friedman and Robert Lucas. In its familiar simplified form, this position places the quantity of money on the determining side of the money–price relation.

    Yet Hume’s account was challenged from the beginning. James Steuart criticized it, Adam Smith held a different view, and Karl Marx later developed a systematic critique in the Contribution to the Critique of Political Economy.

    Gómez Julián calls the alternative reconstructed from Marx the Quantitative Theory of Prices. Its central reversal is that commodity values and prices are not simply passive consequences of a monetary quantity imposed from outside. The amount of money required in circulation is itself conditioned by the values and prices it must express.

    · · ·

    2. Marx’s Critique of Hume

    The paper identifies four central aspects of Marx’s criticism. They matter because the subsequent econometric analysis is explicitly designed to examine propositions derived from this theoretical and historical reconstruction.

    First: circulation is subordinate to production

    In the Marxian framework developed by the paper, money belongs to the sphere of circulation, whereas the value relations that money expresses are ultimately rooted in the sphere of production. The quantity of circulating means of payment must therefore maintain a relation with the prices of the commodities and services being exchanged.

    The paper argues that deviations from the quantity of money socially required for circulation generate corrective movements through the interaction of commodity prices and money. This does not make money powerless: money can affect aggregate demand and thereby feed back into prices. The relationship is therefore reciprocal through time even though the paper treats prices as the ultimately determining side.

    Second: Hume’s evidence arose from a very particular historical episode

    Marx’s epistemological criticism focuses on the historical circumstances behind Hume’s observations. The influx of American gold and silver coincided with changes in the conditions and costs of producing those precious metals.

    From Marx’s perspective, one cannot therefore move automatically from the observed sequence “more precious metal, then higher prices” to the conclusion that an exogenous increase in money caused the general price increase. Gold and silver were themselves commodities whose own values could change.

    The paper emphasizes Marx’s distinction between precious metals entering international exchange as commodities and those same metals acting as domestic means of payment. These adjustments need not occur simultaneously.

    Third: the monetary unit is not identical to the means of circulation

    Marx also criticizes the conflation of accounting money — the unit in which prices are expressed — with money in its concrete role as a means of circulation. For the paper, this distinction is central to deciding what actually functions as the sign of value.

    Fourth: two empirically relevant corollaries

    Two propositions drawn from Marx’s critique
    • Direction: if the monetary unit is the sign of value, the quantity of circulating money depends on the sum of commodity prices; if metallic currency itself is the sign of value, the opposite direction follows. Marx argues for the former.
    • Relative magnitude: under the Marxian formulation, circumstances can exist in which circulating money exceeds the contemporaneous sum of commodity prices. The paper presents this as a point on which the competing logical structures differ.

    The paper operationalizes circulating money as M1 and the sum of commodity prices as nominal GDP. It reports periods in which M1 exceeds nominal GDP in the United States, Canada, the United Kingdom and Brazil, and interprets these observations as evidence consistent with Marx’s second corollary.

    This comparison is evidence within the logical test proposed by the article. It should not be confused with a complete econometric identification of the causal structure connecting all monetary and real variables.

    Money is not treated as an autonomous source from which the whole price system mechanically follows. It is part of a monetary expression of value whose foundations the paper ultimately locates in production and commodity exchange. — The theoretical logic reconstructed in the paper

    The deeper question: what determines value?

    The monetary argument is explicitly tied to Marx’s labor theory of value. In the paper’s reconstruction, capitalist competition generates market prices that fluctuate around centers of gravity grounded in the production process and expressed theoretically through prices of production.

    The author therefore acknowledges that the monetary theory cannot be isolated from the validity or falsity of the broader theory of value on which it rests.

    The paper also discusses the Cambridge Capital Controversies, aggregation problems, the Penn World Table’s treatment of capital remuneration, and the temporal interpretation of the transformation problem. These arguments form part of the theoretical defense surrounding the monetary model; they are not additional empirical results produced by the four-country econometric exercise.

    · · ·

    3. Gold After Bretton Woods

    Extending Marx’s argument into the contemporary period raises an obvious problem. Formal dollar convertibility into gold ended with the collapse of Bretton Woods. If the modern monetary unit nevertheless retains a commodity foundation in some sense, what is the mechanism?

    Gómez Julián argues that gold continued to perform an indirect monetary role after formal convertibility disappeared. The paper combines historical evidence, statements by policymakers, and observed relationships involving gold and the dollar to defend what it calls a “loose gold standard.”

    The paper’s three principal lines of argument
    • Statements by policymakers: particular emphasis is placed on Alan Greenspan’s treatment of gold as an ultimate means of payment.
    • Gold and the dollar: the paper points to their often inverse movement as evidence that gold remains informative about the international value of the dollar.
    • Monetary-policy history: the paper interprets aspects of policy under Volcker and Greenspan, together with the Plaza and Louvre Accords, as attempts to stabilize the dollar in relation to gold and broader commodity prices.

    The distinction between evidence and interpretation is important here. The historical material supports the proposition that gold remained economically and politically relevant after Bretton Woods. Describing the resulting regime as a “loose gold standard” is the author’s theoretical interpretation of that evidence. It is not the same thing as a legally fixed gold convertibility regime.

    The paper extends this interpretation across the tenures of Volcker, Greenspan, Bernanke, Yellen and Powell. Changes in the behavior of gold and the dollar are discussed alongside changes in monetary-policy orientation. These historical comparisons should not be confused with a separate econometric causal identification of the policy regimes themselves.

    The contradiction emphasized through Ernest Mandel

    The paper uses Ernest Mandel to formulate a broader contradiction. An international monetary asset requires stability, yet a national capitalist economy may require monetary flexibility. The dollar therefore performs two roles whose requirements need not always coincide: international money and an instrument of domestic economic expansion.

    The need for an internationally stable monetary unit can conflict with the need for a flexible instrument of domestic economic policy. — The contradiction developed in the paper from Ernest Mandel
    · · ·

    4. The Mathematical Model: Money, Prices and Gold

    The paper condenses its basic theoretical proposition into the following relationship:

    Core equation \[ Q_m = \frac{\lambda_p}{\lambda_{\mathrm{gold}}}\,\beta \]

    \(Q_m\) denotes the circulating money supply, operationalized empirically as M1. \(\lambda_p\) denotes the sum of commodity prices, operationalized as nominal GDP. \(\lambda_{\mathrm{gold}}\) is the international price of gold.

    The coefficient \(\beta\) deserves special attention. It is not itself the velocity of money. In the paper it is defined as the reciprocal transformation:

    Transformation coefficient \[ \beta = \frac{1}{v} \]

    where \(v\) denotes the velocity of circulation. In the basic theoretical exercise, velocity is treated as exogenous and set equal to one, implying \(\beta=1\).

    What follows from the basic equation
    • Holding gold fixed, a higher nominal sum of prices implies a larger quantity of circulating money.
    • Holding prices fixed, a higher gold price implies a smaller quantity of circulating money in the basic specification.
    • When prices and gold move in the same direction, the result for money depends on their relative magnitudes.
    • When prices rise while gold falls, both movements push the basic equation toward a larger quantity of circulating money.

    The paper works through the possible combinations of movements in the two explanatory quantities as a logical consistency exercise. With \(\beta=1\), the equation can also be written in logarithms:

    Logarithmic form \[ \ln Q_m = \ln \lambda_p – \ln \lambda_{\mathrm{gold}} \]

    The logarithmic form motivates elasticity interpretations and can also make empirical relationships easier to model. Crucially, however, the econometric work does not force the gold effect to remain a simple constant negative coefficient.

    The paper therefore introduces the more general relation \(Q_m=f(+\lambda_p,\pm\lambda_{\mathrm{gold}})\): prices are expected to relate directly to circulating money, while the gold relationship is allowed to change direction across different segments or circumstances.

    · · ·

    5. The Data and the Econometric Strategy

    Four countries

    The empirical analysis uses quarterly data from four economies:

    Samples
    • United States: 1959–2022 — approximately 63 years.
    • Canada: 1961–2022 — approximately 61 years.
    • United Kingdom: 1986–2022 — approximately 36 years.
    • Brazil: 1996–2022 — approximately 26 years.

    The paper chooses these countries deliberately. The United States is treated as the most developed Western capitalist case; the United Kingdom as another advanced capitalist economy; Canada as a differentiated welfare-state variant; and Brazil as an emerging economy.

    The author argues that common findings across such cases support a broad generalization about capitalist development. Methodologically, however, evidence from four countries remains cross-country replication across four cases rather than a logical proof that the same result must hold in every capitalist economy.

    Stage 1: pairwise directional comparison

    The first stage compares Bayesian simple linear regressions for three pairs: money and prices, gold and prices, and money and gold. The preferred direction is selected using predictive criteria including ELPD-LOO and, in some cases, the log-fit ratio.

    How to read this step
    • The comparison tells us which regression direction receives stronger predictive support under the paper’s criteria.
    • A comparison between \(Y=f(X)\) and \(X=f(Y)\) does not, by itself, constitute experimental or quasi-experimental causal identification.
    • The paper’s stronger interpretation of causal direction combines the econometric comparison with its historical and theoretical argument.

    Stage 2: testing whether linearity is adequate

    Ramsey RESET tests are applied with quadratic, cubic and combined quadratic–cubic terms and are robustified through Bayesian bootstrapping. The results show very strong evidence against a simple linear form for a number of important relationships, particularly those involving M1.

    But the pattern is not literally identical for every country, every pair and every RESET specification. Some gold–price specifications, for example, do not reject the simpler form under all versions of the test. The faithful conclusion is therefore that nonlinearity is important and often very strong, rather than that every relation is proven nonlinear without exception.

    Stage 3: fitting empirical distributions

    Candidate distributions are fitted to the observed variables through the maximum-goodness-of-fit procedure, with BIC used for comparison. These distributional results are subsequently used to motivate some of the transformations entering the Bayesian generalized linear models.

    Stage 4: Bayesian generalized linear models

    The central multivariate specification models log M1 using nominal GDP and gold. Different statistical families, links and transformations are compared. Gold can enter through a natural cubic spline, allowing its relationship with money to vary over the observed range, or through a transformation based on a fitted distribution.

    Model assessment includes MAE, RMSE, ELPD-LOO, P-LOO, LOO-IC, PSIS-LOO diagnostics, Monte Carlo standard errors and generalized variance-inflation measures. \(R^2\) is used where the statistical family makes the corresponding measure available.

    Stage 5: machine learning and deep learning

    Candidate models
    • Quantile Random Forest (QRF)
    • Conditional Inference Random Forest
    • Bayesian Regularized Neural Network (BRNN)
    • Support Vector Machine with Radial Basis Function kernel (SVMRadial)

    Candidate hyperparameters are compared through repeated cross-validation with 10 folds and 100 repetitions, using a 20% test partition. Performance is assessed through measures including \(R^2\), AIC, MAE, RMSE and deviance comparisons.

    Because the observations are time series, these predictive exercises should be interpreted as results under the paper’s stated resampling design, not automatically as the equivalent of a strictly chronological rolling or walk-forward forecasting experiment.

    Stage 6: ensemble learning

    The paper finally asks whether combinations of models can improve on their individual components. Ensembles are built through a Bayesian generalized linear model with Gaussian family and identity link.

    Among the four national cases, the selected ensemble improves on the individual alternatives in the United States. In Canada, the United Kingdom and Brazil, an individual machine-learning model remains the preferred solution.

    What “objective Bayesian” means here

    The study explicitly describes its Bayesian methodology as objective Bayesian. In operational terms, prior quantities such as prior \(R^2\) and the prior intercept are obtained from preliminary frequentist analyses of the empirical data rather than from elicited subjective beliefs.

    That clarification matters because “objective Bayesianism” can refer to several traditions. In this paper, the practical feature to keep in mind is the empirical anchoring of prior information through preliminary statistical analysis.

    · · ·

    6. Country-by-Country Results

    United States — 1959–2022

    For the simple M1–prices comparison, the paper reports an undecidable result: neither regression direction dominates under the combined log-fit-ratio and ELPD-LOO criteria.

    For the other two pairs, the preferred models are gold as a function of prices and M1 as a function of gold. The author interprets these results, together with the theoretical analysis, as compatible with a prices–gold–money structure. The pairwise regressions alone, however, do not constitute independent causal identification of such a chain.

    RESET strongly rejects the simple linear form in both directions of the M1–prices pair. The price–gold results are more nuanced: one direction shows little evidence against linearity in the reported tests, while the reverse direction shows stronger evidence in at least part of the RESET battery.

    The selected multivariate model is a Gamma BGLM with logarithmic link, with gold represented through a natural cubic spline with five degrees of freedom. The fitted coefficient on log nominal GDP is +0.13.

    The five gold-spline coefficients are \(-0.35\), \(-0.01\), \(-0.04\), \(+0.09\), and \(+0.21\). The important feature is therefore not an alternating sign pattern but the coexistence of negative and positive regions, which is consistent with the paper’s segment-dependent interpretation of the gold–money relation.

    The BGLM reports MAE \(=0.12\) and RMSE \(=0.21\). The subsequent ensemble combines a Bayesian Regularized Neural Network with weight approximately \(0.41\) and a Quantile Random Forest with weight approximately \(0.59\).

    The ensemble reports training \(R^2=0.985\), test MAE \(=0.08\), and test RMSE \(=0.25\). The \(R^2\) figure is specifically a training statistic; it should not be described as a held-out test \(R^2\).

    Canada — 1961–2022

    Canada produces the cleanest pairwise ordering under the paper’s comparison criterion: M1 is preferred as a function of prices, gold as a function of prices, and M1 as a function of gold.

    RESET strongly rejects simple linearity for the money–prices and money–gold relations, while the price–gold results are less uniform across the separate quadratic, cubic and combined tests.

    The selected multivariate specification is a Gamma BGLM with logarithmic link. Gold enters through a transformation associated with the best-fitting Weibull distribution, whose estimated shape is approximately \(5.88\) and scale approximately \(6.47\). The coefficient on log nominal GDP is +0.045.

    The BGLM reports MAE \(=0.23\) and RMSE \(=0.28\). Among the machine-learning alternatives, the Quantile Random Forest performs best under the paper’s criteria.

    Its reported training \(R^2\) is 0.9983, with training MAE \(=0.04\), test MAE \(=0.04\), and test RMSE \(=0.08\). Again, the near-one \(R^2\) belongs to the training sample; the reported test errors are the more relevant numbers for the held-out partition.

    United Kingdom — 1986–2022

    The UK provides an important counterexample to any claim that the pairwise procedure mechanically produces the same answer everywhere. For M1 and prices, the preferred bivariate specification is prices as a function of M1.

    A textual problem in the original paper
    • In Table 12, the row comparing gold and prices prints the “best model” as log(Gold) = f(log(Gold)).
    • That expression is self-referential and appears to be a typographical error in the published table.
    • Rather than silently replacing it with an inferred direction, this summary leaves the preferred bivariate direction for that specific row unresolved.

    For the M1–gold pair, Table 12 does clearly report M1 as a function of gold. The RESET results again reveal substantial nonlinearity, although the exact pattern depends on the functional direction and test specification.

    In the multivariate stage, the selected model is a Gamma BGLM with logarithmic link and a five-degree-of-freedom natural cubic spline for gold. The coefficient on log nominal GDP is +0.071.

    Its gold-spline coefficients include both positive and negative values: \(+0.0001\), \(+0.012\), \(-0.001\), \(+0.006\), and \(+0.01\). The paper interprets this as a gold–money relation whose local direction varies across the relevant range.

    The BGLM reports MAE \(=0.06\) and RMSE \(=0.07\). A Quantile Random Forest is the best-performing machine-learning model, with training \(R^2=0.993\), test MAE \(=0.04\), and a test RMSE reported as approximately zero at the precision shown in the paper.

    Brazil — 1996–2022

    Brazil also differs from Canada. The pairwise comparison prefers prices as a function of M1, prices as a function of gold, and M1 as a function of gold. The original blog description of the gold–prices result as simply “bidirectional” was therefore too loose.

    The Brazilian RESET results contain particularly strong evidence against simple linear specifications: most of the reported posterior-bootstrap mean p-values are zero or very close to zero.

    Brazil is the only country whose selected multivariate model uses a Gaussian family. It nevertheless retains a logarithmic link and a five-degree-of-freedom natural cubic spline for gold. The coefficient on log nominal GDP is +0.05.

    The gold spline again contains coefficients of both signs, and the paper interprets the relationship between gold and circulating money as varying by range. The BGLM reports MAE \(=0.07\) and RMSE \(=0.21\).

    Among the machine-learning candidates, SVMRadial performs best under the paper’s comparison. It reports training \(R^2=0.991\), test MAE \(=0.012\), and test RMSE \(=0.016\).

    The clearest regularity across the four selected multivariate models is narrower than a claim of econometrically proven one-way causality: nominal GDP enters the M1 equation with a positive coefficient in every country, while the modeled gold–money relation is nonlinear or transformation-dependent.
    · · ·

    7. Feedback, Complexity and Monetary Non-Neutrality

    The paper’s explicit conclusion is strong: money is not neutral in either the short run or the long run. It reaches this conclusion within a theoretical framework whose explanation differs fundamentally from the standard Quantity Theory.

    Non-neutrality is not attributed to circulating money unilaterally determining prices. Instead, the paper proposes a feedback mechanism: prices condition the required amount of circulating money through the exchange value of the monetary unit and its real foundation, while money can feed back into prices through aggregate demand.

    The econometric evidence shows important nonlinear relationships among M1, nominal GDP and gold. The author combines those results with the theoretical feedback mechanism and describes the resulting relation as a complex system.

    What should be distinguished
    • The empirical models directly analyze M1, nominal GDP and gold.
    • Conventional monetary-neutrality tests are often formulated in terms of lasting effects of monetary variables on real variables such as real output or employment.
    • The paper’s conclusion of non-neutrality at every horizon therefore belongs to its broader theoretical and empirical synthesis; the four-country models are not a separate standard horizon-by-horizon neutrality test on real output and employment.

    The same distinction helps with the paper’s use of complexity and chaos theory. Evidence of nonlinearity and feedback supports the claim that simple linear descriptions are inadequate. It does not, by itself, constitute an empirical demonstration of deterministic chaos through quantities such as a positive Lyapunov exponent or a strange attractor.

    · · ·

    8. Policy Implications and the Questions Still Open

    Direct price intervention and monetary policy

    The policy argument contains two conclusions that are compatible within the paper’s feedback framework.

    Policy conclusions developed in the paper
    • Act on the determinants of prices themselves. Because the theory ultimately roots prices in production and competition, the author argues that interventions affecting the real determinants of costs and prices are the most direct route to price control.
    • Monetary contraction can nevertheless influence prices. The feedback mechanism allows changes in M1 to affect aggregate demand and therefore feed back into prices even though M1 is not treated as the ultimately determining variable.
    • Major crises cannot necessarily be reduced to monetary policy alone. The discussions of the Great Depression and the 2008 crisis are used against an exclusively monetary explanation and in favor of including fiscal, financial and real-economy mechanisms.
    • Gold and employment stability. The paper disputes the claim that attention to a gold anchor is necessarily incompatible with employment stability. This is a historical-policy argument of the paper rather than a causal effect separately estimated by the four-country regressions.

    Two questions the paper explicitly leaves unresolved

    The conclusion does not pretend that the contemporary monetary mechanism has been fully identified. It explicitly opens two further research problems.

    First: if the post-Bretton-Woods relationship is indeed the loose gold arrangement proposed by the paper, how exactly do policy instruments mediate the feedback among prices, gold and M1? Interest rates, monetary expansions and contractions, and other policy tools would have to enter the system as mediating or latent variables.

    Second: if money is non-neutral, what are the quantitative and temporal limits of that non-neutrality? How far can M1 deviate from the level required for circulation, and how long does the proposed coercive correction through prices take?

    The paper suggests that answering the second question could also provide a different perspective on phenomena such as the liquidity trap.

    What the machine-learning layer contributes

    One unusual aspect of the research is methodological. A monetary argument rooted in Marx’s nineteenth-century critique is examined using Bayesian inference, posterior-bootstrap specification tests, generalized models, random forests, a Bayesian regularized neural network, support-vector machines and ensemble learning.

    These tools strengthen the analysis by asking whether flexible models reproduce the statistical relationships and by comparing predictive performance across alternative specifications. What they do not do automatically is transform observational association into causal identification.

    The paper’s causal interpretation therefore remains a synthesis of historical reasoning, theoretical structure and econometric evidence, rather than something supplied by machine learning alone.

    · · ·

    The Takeaway

    The most defensible summary of the paper is more precise than either “money causes prices” or “prices cause money.” Its theoretical framework is asymmetric but reciprocal: prices are treated as ultimately determining the quantity of circulating money, while money can feed back into prices through aggregate demand.

    The empirical evidence does not mechanically return the same bivariate direction in every country. The U.S. money–prices comparison is undecidable under the paper’s criterion; Canada favors M1 as a function of prices; and the United Kingdom and Brazil favor prices as a function of M1 in the simple pairwise comparison.

    What is common across all four selected multivariate models is that nominal GDP enters positively in the M1 equation, while the gold term requires a nonlinear or transformed representation. That cross-country result is the clearest econometric regularity supporting the paper’s broader theoretical construction.

    The author then interprets these findings through Marx: the quantity of circulating money is ultimately subordinated to the price and value structure it expresses, yet it remains capable of affecting the system that determines it. From this feedback the paper derives its claim of monetary non-neutrality.

    The study is strongest when its econometrics is read together with its historical and theoretical argument: the statistical models test relationships implied by the theory, but they do not make the theory unnecessary. — A careful reading of the scope of the evidence

    That also defines the next research frontier: explicitly modeling the policy instruments mediating the gold–money relation, identifying the temporal dynamics of the feedback more directly, testing monetary neutrality against real variables, and replicating the framework across additional countries and monetary regimes.

    Read the Full Paper on arXiv

    Quantitative Theory of Money or Prices? A Historical, Theoretical, and Econometric Analysis — Gómez Julián, J. M. (2025)

  • The wage price spiral refuted

    Do ‘excessive’ wage rises lead to rising inflation and thus drive economies into a wage-price spiral?  Back in 1865, at the International Working Men’s Association, Marx debated with IWMA Council member Thomas Weston.  Weston, a leader of the carpenter’s union, argued that asking for increased wages was futile because all that would happen would be […]

    The wage price spiral refuted