Espartaco

“Is that to say we are against Free Trade? No, we are for Free Trade, because by Free Trade all economical laws, with their most astounding contradictions, will act upon a larger scale, upon the territory of the whole earth; and because from the uniting of all these contradictions in a single group, where they will stand face to face, will result the struggle which will itself eventuate in the emancipation of the proletariat.”

Karl Heinrich Marx · Marx-Engels Collected Works, Vol. VI, p. 290

26,453 views since December 2020

26,453 visitas desde diciembre de 2020

EnglishEspañol

Category: Political Science

  • ON THE NEGATIVE BINOMIAL 2 DISTRIBUTION

    ON THE NEGATIVE BINOMIAL 2 DISTRIBUTION

    Probability · Count Data · Hierarchical Models

    When Counts Refuse to Behave: Understanding the Negative Binomial II as a Measurement Instrument

    A guided reading of José Mauricio Gómez Julián’s 2020 essay Some Reflections on the Negative Binomial Distribution II as a Measurement Instrument—tracing the argument from geometric series and probability mixtures to overdispersion, latent heterogeneity, and simulation in R.

    Mauricio Gómez Julián · Theoretical & Applied Probability · Approx. 15-minute read
    Reading note. This essay explains the paper on its own terms while keeping the mathematics technically precise. Where a qualification is needed—especially in the passage from an exponential mixing distribution to the general Negative Binomial II—it is marked explicitly rather than silently altering the paper’s argument.

    The question behind the paper

    Count data appear everywhere. An economist counts firm failures, strikes, defaults, patents, accidents, or entries into a market. A political scientist counts protests, cabinet changes, violent events, legislative vetoes, or international disputes. A biologist counts surviving organisms, mutations, infections, or offspring. The elementary model for many such problems is the Poisson distribution. But real counts often fluctuate more than a Poisson model allows. Their variance is larger than their mean: the data are overdispersed.

    The Negative Binomial II—usually abbreviated NB2—is one of the central statistical instruments for precisely that situation. Yet Gómez Julián’s paper is not content to present the NB2 probability mass function, list its moments, and move on. Its organizing question is broader: what kind of object is a probability distribution, where does it come from, what other distributions does it contain or presuppose, and what is gained when we understand its construction rather than merely its final formula?

    The paper therefore has two explicit axes. The first, and more important one, studies NB2 as the outcome of a wider theoretical structure involving hierarchical models and probability mixtures. The second studies NB2 as an individual distribution—its form, interpretation, moments, and practical use, including hand calculations and R. The intended unity between these axes is philosophical as well as mathematical: probability distributions are treated as instruments for measuring natural and social phenomena under uncertainty, and the paper argues that their history, formal structure, scientific interpretation, and application should not be torn apart.

    The distribution is easier to understand when we see not only the finished formula, but also the process that produces it.
    · · ·

    Why begin with the geometric series?

    The paper begins surprisingly far away from count-data regression: with the geometric series, its historical roots, and its relation to the binomial theorem. This is deliberate. Gómez Julián wants the reader to see the Negative Binomial II as part of a mathematical genealogy rather than as a formula that appeared fully formed.

    The route is roughly this: the geometric series provides a simple infinite expansion; differentiation exposes a recurring combinatorial pattern; that pattern is used to motivate the binomial expansion; and replacing the ordinary exponent with a negative one leads to the negative binomial series. The point is not merely algebraic. The paper repeatedly emphasizes the movement from simpler structures to more general ones and from one family of mathematical objects to another.

    1 + x + x2 + x3 + ··· = 1 / (1 − x),   |x| < 1 binomial expansion negative binomial series The paper’s algebraic genealogy in compressed form

    For a nontechnical reader, the important idea is simple: a probability distribution can be understood through the transformations and relationships that generate it. The paper later reinforces this visually with a large network diagram of probability distributions, reproduced from ProbOnto, in which distributions are connected by transformations, limiting relations, and special cases. NB2 is therefore presented as one node in a densely connected mathematical ecology, not as an isolated technique.

    Probability as a measurement problem

    Before building the NB2, the paper stops to ask what “probability” means. This is not a decorative philosophical detour. Gómez Julián’s position is that formal probability calculus and philosophical interpretation cannot be completely divorced, because statistical conclusions depend on what we think probabilities are measuring and on how the scientific problem is conceptualized.

    The paper adopts an explicitly objective and dialectical-materialist orientation. Randomness is treated primarily as an epistemological condition: events appear random because their causes are unknown, too numerous, or too complicated to represent completely. At the same time, the Kolmogorov axioms provide the formal mathematical framework that makes probability calculations coherent. The paper also draws on objective Bayesianism to argue that degrees of belief should be constrained by evidence, scientific theory, and the probability calculus rather than reduced to arbitrary personal opinion.

    Why this matters statistically

    A model is not chosen only because its formula is convenient. The scientific description of the process determines which random variables, conditional relationships, latent quantities, and parameterizations are meaningful. That principle becomes concrete once the paper turns to hierarchical models.

    A family, not an isolated formula

    The paper next introduces the distributions needed for its construction: Bernoulli, Binomial, Poisson, and Exponential. Each plays a distinct role.

    Distribution Plain-language role Role in the paper
    Bernoulli One trial with two possible outcomes. The elementary unit from which repeated success/failure experiments are built.
    Binomial Counts successes in a fixed number of Bernoulli trials. The first level of the hierarchical construction.
    Poisson Counts occurrences when events arrive with a given mean rate. Makes the number of opportunities or events itself random.
    Exponential Models waiting time or positive continuous variation associated with a Poisson process. Introduces variation in the Poisson rate across observational units.

    This sequence already contains the paper’s methodological intuition. A complex phenomenon can be decomposed into simpler probabilistic stages, each corresponding to a different part of the scientific story. Instead of forcing all uncertainty into a single flat formula, a hierarchical model lets uncertainty enter at more than one level.

    Hierarchies, mixtures, and latent variables

    A hierarchical model specifies variables and parameters in stages. A mixture model appears when a parameter in one probability distribution is itself treated as a random quantity governed by another distribution. The parameter that seemed fixed at the lower level becomes variable at the higher level.

    That is the key conceptual move in the paper. It is also why Gómez Julián brings in the language of latent variables: some of the forces producing observed variation may not be directly observed, but their consequences can still be represented probabilistically. In applied work, this is familiar. Two factories, municipalities, firms, hospitals, or individuals may face different underlying event rates even if we initially write one common Poisson equation for all of them.

    The paper links this mathematical construction to the Hegelian distinction between Being-in-itself and Being-for-itself. Stripped of the philosophical vocabulary, its statistical meaning is fairly intuitive. Studying NB2 “in itself” means studying the wider process and network of relationships from which it emerges. Studying NB2 “for itself” means taking the marginalized distribution as a distinct object and examining its own formula, parameters, moments, and applications.

    The first mixture: Binomial inside Poisson

    The first major construction uses a biological example. Imagine an insect that lays many eggs. Conditional on a mother having laid Y eggs, each egg survives independently with probability p. The number of surviving eggs, X, is therefore Binomial. But instead of fixing the number of eggs Y, the paper lets it vary according to a Poisson distribution with mean λ.

    X | Y ~ Binomial(Y, p)
    Y ~ Poisson(λ) First hierarchical model

    Marginalizing means asking for the distribution of X after summing out the intermediate variable Y. Algebraically, we combine all the possible values of Y, weighted by how probable each one is. The result is elegant:

    X ~ Poisson(λp) After marginalizing over Y

    In modern probability language, this is a version of Poisson thinning. If the total number of opportunities is Poisson and each opportunity independently survives with probability p, then the surviving count is also Poisson, with its mean reduced from λ to λp. The paper also derives the same conclusion through iterated expectations:

    E[X] = E{E[X | Y]} = E[pY] = pλ

    For the paper, this is more than a computational trick. It shows how a hierarchical process that appears to contain two random layers can be “compressed” into a simpler marginal law without erasing the scientific interpretation that motivated the hierarchy.

    When the Poisson rate itself varies

    The next step introduces another level of heterogeneity. Suppose there are many insect mothers, and the Poisson mean is not the same for every mother. The paper now treats the rate itself as random:

    X | Y ~ Binomial(Y, p)
    Y | Λ ~ Poisson(Λ)
    Λ ~ Exponential(β) Three-stage hierarchy in the paper

    The statistical intuition is important. Variation does not occur only in the observed count; it can also occur in the underlying rate that generates the count. Once the rate differs across observational units, the final distribution becomes more dispersed than a single-rate Poisson model. This is precisely the kind of latent heterogeneity that makes the negative binomial family useful in economics, epidemiology, demography, political science, and many other count-data settings.

    The paper shows that the mean of the full hierarchy can be obtained by repeatedly conditioning and averaging, arriving at E[X] = pβ under its parameterization. It then integrates out the random Poisson rate and identifies the resulting expression with the negative binomial form.

    Technical qualification added for accuracy

    There is an important distinction here. An Exponential distribution is a Gamma distribution with shape parameter equal to 1. Therefore, a Poisson–Exponential mixture produces the geometric distribution, which is a special case of the negative binomial with r = 1. The general NB2 with arbitrary dispersion parameter r arises from a Poisson–Gamma mixture. Thus, the paper’s core intuition—random heterogeneity in the Poisson rate generates negative-binomial-type overdispersion—is correct, but the fully general NB2 requires the Gamma mixing family rather than the Exponential distribution alone.

    This qualification actually sharpens the paper’s broader message. The geometric distribution, the exponential distribution, the gamma family, Poisson processes, and the negative binomial are not unrelated objects. They sit inside a network of special cases and mixture relationships. The more general Gamma mixing distribution preserves the same hierarchical logic while extending the model beyond the r = 1 case.

    · · ·

    The NB2 “for itself”: what the finished distribution tells us

    Once the hierarchy has been “compressed,” the paper turns to the Negative Binomial II as an object in its own right. One common parameterization writes the probability of observing x failures before the r-th success as:

    P(X = x) = Γ(x + r) / [Γ(r) Γ(x + 1)] · pr · (1 − p)x,   x = 0, 1, 2, …

    Here, p is the success probability and r is the target number of successes. The distribution answers a reversed version of the familiar Binomial question. The Binomial asks: how many successes occur in a fixed number of trials? The negative binomial asks: how many failures occur before a fixed number of successes is reached?

    The paper’s most important statistical property appears in its first two moments. With q = 1 − p:

    μ = E[X] = rq / p
    Var(X) = rq / p2 = μ + μ2/r

    That final equality is the bridge to modern count-data econometrics. The Poisson distribution imposes Var(X) = μ. NB2 allows:

    Var(X) = μ + αμ2,   where α = 1/r

    In other words, variance can grow faster than the mean. The smaller r is—or, equivalently, the larger the heterogeneity parameter α is—the more dispersion the model permits. As heterogeneity vanishes, NB2 approaches the Poisson benchmark. This is why the paper presents NB2 as a more flexible instrument for count data when the Poisson equality between mean and variance is too restrictive.

    Feature Poisson Negative Binomial II
    Mean μ μ
    Variance μ μ + αμ²
    Extra heterogeneity Not separately modeled Captured through α (or r)
    Typical use Equidispersed counts Overdispersed counts

    For an econometrician, this variance function is often the fastest route to understanding NB2. For a broader reader, an intuitive translation is enough: NB2 expects the world to be more uneven than a simple Poisson process. Some units have persistently higher event rates than others; unobserved conditions vary; clusters form; the same mean can coexist with much wider dispersion.

    The maintenance example: counting failures before the fourth alarm

    The paper gives a concrete industrial interpretation. Imagine fixed capital—a machine—producing parts. A part is either satisfactory or defective. A monitoring system treats a defective part as the event of interest because it signals the need for maintenance. Assume independent Bernoulli trials and a constant defect probability.

    Gómez Julián sets r = 4, p = 0.005, and asks for the probability of observing exactly x = 100 failures before the fourth success, using the negative binomial mass function. Substitution gives:

    P(X = 100 | r = 4, p = 0.005) ≈ 0.000067

    The number is tiny—about 6.7 chances in 100,000. The statistical interpretation is not that “100 failures happen and then four successes happen” as two separate blocks. Rather, among an ongoing sequence of independent trials, exactly 100 non-events occur before the fourth event of interest is reached.

    The paper checks the result manually, with a Texas Instruments calculator, and with R. It then plots the corresponding distribution, illustrating how a small success probability pushes substantial probability mass toward relatively large counts before the required number of successes is accumulated.

    What the R simulation is trying to show

    The final applied part of the main text shifts from evaluating a probability to generating pseudo-random data. The paper constructs a custom card-drawing experiment: repeatedly sample from a 52-card deck until a specified rank appears, record how many draws were required, and repeat the experiment many times. It then compares the histogram produced by that “from first principles” counting procedure with a histogram generated by R’s built-in rnbinom function.

    The figures for 50, 100, 150, and 200 repetitions show the same qualitative pattern: a strongly right-skewed count distribution with many small values and a long tail. The pedagogical purpose is clear. Software is not magic. A built-in random generator is implementing a probabilistic structure that can also be approximated through an explicit sequence of elementary trials.

    A convention to watch in R

    R’s rnbinom convention counts the number of failures before a specified number of successes. A hand-built routine that counts the total number of draws including the successful draw differs by one when size = 1. For an exact one-to-one comparison, the manual routine and the software call should use the same counting convention. This does not erase the pedagogical point of the simulation, but it matters for exact numerical equivalence.

    The broader lesson is useful far beyond R. Simulation can reveal what a distribution means operationally: not merely how its formula looks, but what repeated mechanism would generate data with that shape.

    NB1, Bayes, and the annexes: why the paper keeps widening the frame

    The annexes extend the same relational approach. The paper distinguishes NB2 from NB1, emphasizing that different negative-binomial parameterizations answer slightly different counting questions. In the NB1 presentation used there, the random variable is the total number of Bernoulli trials needed to reach r events of the chosen type; in the NB2 presentation, the random variable is restricted to the number of failures before those r successes.

    The paper also returns to conditional probability, total probability, inverse probability, and objective Bayesianism. This may seem far removed from overdispersed count data, but it serves the same philosophical thesis: statistical formulas must be understood through the relationships they encode. Conditional probability is not merely a ratio; it represents a structured dependence between events. Bayesian updating is not merely algebra; it connects prior knowledge, evidence, and posterior assessment.

    Finally, the paper gives a more general NB2 expression in terms of the Gamma function and reports estimators based on the first two sample moments. This again links the abstract distribution to empirical work: the population parameters acquire meaning only because sample information provides a route to estimation.

    What should we take away?

    Gómez Julián’s paper is best read as an extended argument against treating the Negative Binomial II as a black-box formula. Its distinctive contribution is not a new NB2 estimator or a new regression algorithm. It is an attempt to reconstruct the distribution through several layers at once: historical, algebraic, probabilistic, computational, applied, and philosophical.

    For the nontechnical reader, the central statistical lesson can be stated in one sentence: when counts vary more than a single-rate Poisson model permits, the extra variability can often be understood as heterogeneity in the underlying event rate, and the negative binomial family provides a natural way to represent it.

    For the econometrician, the key signature is the NB2 variance function, Var(Y) = μ + αμ². For the mathematician, the paper is an invitation to follow the transformations linking geometric series, binomial expansions, gamma functions, conditional distributions, and marginalization. For the philosopher of science, its central claim is methodological: the formal instrument, the scientific object, the history of the instrument, and the interpretation of uncertainty should be studied in relation rather than isolation.

    And for the applied researcher, perhaps the most useful question is the simplest one: what process would have to be operating for this distribution to be a sensible measurement instrument? Once that question is asked, NB2 stops being just a convenient correction for overdispersion. It becomes a hypothesis about how heterogeneity enters the data-generating process.

    A distribution is most informative when its probability law and its generating story tell the same scientific story.
    In one compact map

    Bernoulli gives the elementary success/failure trial; Binomial aggregates such trials at a fixed size; Poisson makes the number or rate of occurrences stochastic; Gamma heterogeneity lets that Poisson rate vary across units; marginalizing the latent rate yields the Negative Binomial II, whose variance can exceed its mean.

    This explainer follows the architecture and substantive aims of Gómez Julián’s paper while separating the paper’s own philosophical framing from the technical qualifications added here for mathematical precision.

    Read the Original Paper ↗
    Editorial-academic layout · Playfair Display · Lora · DM Mono
  • RATE OF PROFIT, UNIT ROOTS, AND NON-STATIONARITY OF TIME SERIES

    Political Economy · Econometrics · Time Series

    When Economies Do Not Return

    Unit Roots, Profitability, and Marx’s Falling Rate of Profit

    A guided reading of José Mauricio Gómez Julián’s 2020 essay on non-stationarity, permanent economic shocks, investment, and the long-run dynamics of capitalist profitability.

    GÓMEZ JULIÁN · 2020 · EXPLAINER · ≈ 15 MIN READ

    1. The question beneath the statistics

    A recession ends. Factories reopen, employment begins to rise and gross domestic product starts growing again. But has the economy actually returned to the path it was following before the crisis? Or has the crisis changed the path itself?

    That deceptively simple question sits at the heart of Gómez Julián’s essay On the Law of the Tendential Fall in the Average Rate of Profit: Unit Roots and Non-Stationarity of Time Series. The paper brings together a technical problem in time-series econometrics and a much older problem in political economy: Karl Marx’s claim that the average rate of profit is subject to a long-run tendency to fall.

    The connection may initially seem strange. A unit root belongs to the vocabulary of stochastic processes, forecasting and econometrics. Marx’s falling rate of profit belongs to theories of accumulation, technological change, crisis and class relations. Gómez Julián’s argument is that they meet at one fundamental idea: economic history may leave permanent traces.

    If shocks alter the future path of an economy rather than merely disturbing it temporarily, history is not noise around the model. History becomes part of the model.

    The paper therefore treats non-stationarity as more than an annoying statistical property that must be removed before running a regression. It interprets it as evidence against a picture of capitalism in which every disturbance is followed by an automatic return to an unchanged long-run equilibrium.

    The route from that proposition to Marx, however, has several stages. Understanding them separately is the easiest way to see both what is powerful about the argument and where econometric caution is required.

    · · ·

    2. Stationarity: does the economy forget?

    In everyday language, something stationary remains roughly where it is. In time-series analysis the meaning is more precise. A weakly stationary process has a constant mean and variance through time, and the covariance between two observations depends on how far apart they are—not on the historical date at which they occur.

    The intuitive issue is memory. Imagine an economic variable fluctuating around a stable center. A recession pushes it downward, but forces inside the system progressively pull it back. Given enough time, the effect of the original shock fades. The process “forgets.”

    Now imagine another process. A negative shock pushes the variable downward and the next period begins from that lower level. Later shocks are added to everything that happened before. The effects accumulate. There is no built-in statistical mechanism guaranteeing a return to the old path. This second world is the natural habitat of the unit root.

    Process What happens after a shock? Long-run intuition
    Stationary The shock gradually dies out. The series tends to return toward a stable distribution.
    Trend-stationary The shock dies out around a deterministic trend. The long-run path moves predictably with time.
    Difference-stationary The shock changes the level of the series permanently. The level follows a stochastic trend; differences may be stationary.

    This distinction matters enormously for economics. If output is trend-stationary, a recession is essentially a temporary displacement from a pre-existing trajectory. If output contains a unit root, the recession can change the trajectory from which the future proceeds. Growth may resume without the lost output ever being recovered.

    A useful distinction

    Recovery of the growth rate is not the same thing as recovery of the level. An economy can start growing at 3 percent again while remaining permanently poorer than it would have been had the crisis never occurred.

    3. What a unit root actually means

    The paper introduces the idea through the simplest autoregressive model. Let the current value of a variable depend on its previous value plus a new disturbance:

    Yt = ρYt−1 + ut ρ is the autoregressive coefficient; ut is the new shock.

    When the absolute value of ρ is below one, the influence of an old shock becomes progressively smaller. The process is mean-reverting under the usual conditions. But when ρ = 1, we obtain:

    Yt − Yt−1 = ut or, equivalently, ΔYt = ut

    This is the canonical random walk. Today’s level contains yesterday’s level in full. Every shock is therefore incorporated into the future path. The variance of the level grows with the horizon, and conventional statistical inference applied mechanically to such levels can become misleading.

    This is why unit roots are associated with the famous problem of spurious regression. Two unrelated trending series can produce an impressive coefficient, a high R-squared and apparently significant test statistics simply because both contain persistent stochastic trends.

    The econometric response is not to declare all relationships between non-stationary variables meaningless. Rather, researchers ask whether the variables are cointegrated—whether some stable long-run combination of them exists—or otherwise transform and model the series in a way consistent with their integration properties.

    Technical translation

    A unit root does not mean that a variable literally moves at random in every economically relevant sense. It means that, within the statistical representation, shocks to the level are not forced to disappear. The economic interpretation of those shocks still requires theory.

    · · ·

    4. The Mankiw–Krugman dispute: will lost output come back?

    Gómez Julián devotes a substantial part of the paper to a remarkably public argument that unfolded after the 2008 financial crisis. The Obama administration’s Council of Economic Advisers expected a strong rebound. The underlying intuition was familiar: unusually weak growth during a recession should eventually be followed by unusually strong growth as the economy returns toward normal.

    Gregory Mankiw objected. Drawing on earlier work with John Campbell, he argued that aggregate output behaves much more persistently than the conventional picture of temporary deviations from a stable trend would suggest. If a fall in output can have a permanent component, then one cannot simply assume that everything lost during a recession will be recovered through subsequent above-normal growth.

    Conditional recovery versus unconditional forecasting

    Mankiw’s point was subtler than “recoveries never happen.” If one knew with certainty that a recession had ended, then strong post-recession growth might indeed be likely. But a forecast made in real time does not possess that information. There remains some probability that the recession will continue, that another contraction will follow, or that part of the loss reflects a permanent change rather than temporary under-utilization.

    Arnold Kling supplied an especially intuitive version of the contrast. Suppose output is low because frightened households temporarily postpone purchases. Once fear disappears, spending can rebound: that resembles a trend-stationary story. But suppose resources have been committed to the wrong houses, technologies or forms of human capital. Those resources cannot simply be unspent. The economy may grow again, but some of the loss remains in history.

    Krugman and DeLong: look at unemployment

    Paul Krugman and Brad DeLong approached the problem from another angle. High unemployment and low capacity utilization indicate unused resources. If unemployment is far above normal, they argued, one should expect it to fall; combined with Okun’s law, that creates a case for unusually rapid output growth during recovery.

    DeLong supported the argument with a relationship between unemployment and subsequent GDP growth. Mankiw’s response was econometric rather than rhetorical: he suspected that the apparent relationship was being driven disproportionately by observations surrounding the exceptionally strong recovery after the 1981–82 recession.

    The subsequent calculations discussed in Gómez Julián’s paper were revealing. For the full sample, the regression produced an adjusted R-squared of about 11 percent and a t-statistic of 3.5. Removing eight quarters associated with the Reagan-era rebound reduced the adjusted R-squared to about 5 percent and the t-statistic to 2.1. The relation did not literally vanish, but its apparent strength became substantially more dependent on a particular historical episode.

    A later study by David Cushman, also reviewed in the paper, went further. Cushman asked what a conventional econometric forecaster working in 2009 might have concluded. His results supported Mankiw’s skepticism about the stronger rebound projections and judged DeLong’s dynamic Okun-law specification to perform poorly relative to alternative forecasts.

    Why this episode matters for the paper

    Gómez Julián treats this debate as empirical evidence against automatically assuming mean reversion in macroeconomic aggregates. The central issue is not whether recessions are followed by recoveries. They usually are. The issue is whether a recovery necessarily restores the counterfactual path that existed before the recession.

    5. From persistent shocks to profitability

    At this point the paper changes scale. The argument is no longer merely about forecasting GDP after a recession. Gómez Julián asks what kind of economic mechanism could make history matter so persistently.

    Olivier Blanchard provides an important bridge. Writing about financial crises, Blanchard observed that, across countries, output often does not return to its old trend path after a crisis. Instead, the economy can remain permanently below it. That is a profound distinction: the rate of growth can normalize while the level of productive activity remains permanently reduced.

    Gómez Julián then connects this phenomenon to Marxian political economy. Marx’s law of the tendential fall in the rate of profit is not a claim that profitability must decline mechanically every year. It is a claim about a long-run force generated by capitalist accumulation, operating through a system that also contains counteracting influences and recurrent cyclical recoveries.

    In broad Marxian terms, profit must be evaluated relative to the capital advanced to obtain it. Technical development raises productivity, but capitalist competition also encourages firms to substitute machinery, infrastructure and other forms of accumulated capital for living labor. The paper emphasizes the resulting relationship between the organic composition of capital, profitability and the development of productive forces.

    The crucial insight is that a cyclical rebound and a secular tendency are perfectly compatible. A profit rate can fall, recover sharply, experience another boom and still exhibit a lower long-run trajectory across successive historical cycles.

    Figures 4–7 in the paper Gómez Julián reproduces estimates assembled by Michael Roberts showing a declining long-run rate of profit for major G20 economies, a rising organic composition of capital alongside falling profitability, and a longer historical series in which repeated recoveries occur inside a broader downward movement. The figures are used as corroborating evidence for the Marxian tendency, not as new estimates produced by Gómez Julián himself.

    This is the point at which non-stationarity acquires its political- economic meaning in the paper. If crises leave lasting scars, and if the variable organizing accumulation itself evolves historically, then “returning to normal” cannot simply mean returning to an eternal statistical center. What counts as normal after one historical cycle may already differ from what counted as normal before it.

    6. Do profits lead investment?

    The argument still requires another link. Even if profitability follows an important long-run trajectory, why should it organize the broader movement of output and employment? Gómez Julián’s answer is investment.

    Investment expands productive capacity, creates demand for machinery and construction, reorganizes labor and shapes future production. If changes in profitability systematically precede changes in investment, then profitability becomes a plausible transmission mechanism between Marx’s theory of accumulation and the macroeconomic path observed in time-series data.

    Kothari, Lewellen and Warner Using U.S. corporate data, they find that profits and stock returns predict changes in investment up to roughly a year and a half ahead and absorb much of the predictive content attributed to variables such as interest rates, volatility, credit spreads and Tobin’s q.
    Michael Roberts The paper uses Roberts’s international estimates of profitability to argue that the long-run decline is visible not merely in a single recession but across a much broader historical sequence of booms, crises and partial recoveries.
    José A. Tapia Granados Using 251 quarters of U.S. data, Tapia compares competing endogenous theories of the business cycle and reports evidence more consistent with profits leading investment than with investment independently determining subsequent profits.

    Tapia’s result is particularly important for Gómez Julián because it reverses a familiar Keynesian or Minskyan narrative in which autonomous investment “calls the tune.” In the interpretation favored by the paper, expected profitability is what gives capitalists the incentive to accumulate. Investment therefore reacts to profit conditions, and movements in profitability propagate into the wider economy.

    Figures 8–11 The tables reproduced from Tapia show the behavior of profits, investment and wages around U.S. expansions and recessions; regressions in which lagged profits help explain investment; and Granger-causality tests in which profits contain substantial predictive information for subsequent private fixed investment.

    The paper’s final causal picture can therefore be reconstructed as a sequence:

    The proposed chain

    profitability → investment → production and employment → crisis/recovery path

    If profitability is historically conditioned, and investment depends strongly on profitability, then successive periods of accumulation do not begin from a clean slate. Each begins with a capital stock, a profit environment and a productive structure inherited from the preceding period.

    · · ·

    7. What the evidence can—and cannot—establish

    This is also where precision becomes especially important. The paper brings together several empirical facts that can be mutually reinforcing, but they are not logically interchangeable. A careful reading should keep four distinctions in view.

    Four econometric guardrails

    • A unit root does not imply a downward trend. It implies persistence: shocks to the level need not disappear. A unit-root process can wander upward, downward or in both directions. The sign of a long-run profitability tendency must come from additional theory and evidence.
    • A falling series need not contain a unit root. A variable may decline around a deterministic trend while its deviations from that trend remain stationary. “Falling” and “non-stationary” answer different statistical questions.
    • Economic plausibility does not by itself eliminate spurious regression. Temporal precedence and a strong substantive mechanism are important for causal interpretation, but regressions among persistent series still require appropriate treatment of unit roots, cointegration and dynamic specification.
    • Granger causality is predictive, not automatically structural. If profits Granger-cause investment, past profits improve forecasts of investment conditional on the model. That is meaningful evidence about temporal ordering, but additional assumptions are required to establish the full causal mechanism.

    These qualifications do not destroy Gómez Julián’s central argument. They make its strongest defensible form clearer.

    Non-stationarity contributes evidence for persistence and historical dependence. Blanchard contributes evidence that major crises can leave output permanently below its old trajectory. The profitability literature cited by Gómez Julián contributes a separate claim: the average rate of profit displays a long-run declining tendency. Kothari, Lewellen and Warner and Tapia contribute another link: profitability contains important information about subsequent investment.

    The Marxian conclusion emerges from the combination of these propositions, not from the unit root alone.

    Non-stationarity supplies the memory. Profitability supplies the direction proposed by the theory. Investment supplies the transmission mechanism.

    This distinction is essential because it transforms a potentially overextended statistical claim into a much richer research program. Instead of asking whether one test can “prove Marx,” the relevant questions become: How persistent are shocks to output and profitability? Are breaks temporary or permanent? How should the profit rate itself be measured? Does profitability lead accumulation across countries and historical regimes? And does the long-run trajectory survive alternative specifications?

    Those are empirical questions—and therefore questions on which Marxian, Keynesian and mainstream econometric approaches can genuinely confront one another using evidence.

    8. Why this matters beyond econometrics

    It would be easy to treat the unit-root controversy as a specialist dispute about the properties of an autoregressive coefficient. Gómez Julián’s paper insists that much more is at stake.

    Consider the expression the economy will return to normal. It sounds descriptive, almost innocent. Statistically, however, it embeds a hypothesis. It assumes that there exists some stable reference path toward which the economy tends to return after a disturbance.

    If the process is strongly path-dependent, that assumption may fail. A banking crisis can destroy firms, interrupt careers, cancel investment projects and alter the capital stock. A prolonged recession can change the composition of production. Investment not undertaken today means productive capacity that does not exist tomorrow. The future therefore reflects not only current conditions but also the sequence by which those conditions were reached.

    For political scientists, this has an immediate implication. Economic crises cannot always be understood as temporary deviations after which politics resumes on an unchanged material foundation. If output, employment, investment and profitability carry historical scars, then crises can alter the terrain on which subsequent distributional conflicts and policy decisions occur.

    For economists, the message is equally important. Choosing between a stationary and non-stationary representation is never merely a cosmetic preprocessing decision. It changes what the model says an economic shock is. In one representation, the shock is a temporary displacement. In another, it becomes part of the state from which all subsequent development proceeds.

    And for readers of Marx, the paper offers an unusual bridge between nineteenth-century political economy and modern time-series reasoning. Marx’s theory is historical in structure: accumulation changes the conditions under which the next round of accumulation occurs. Gómez Julián’s use of non-stationarity gives that historical intuition a statistical analogue. The economy need not circle eternally around an unchanged center because the process itself can transform the point from which the next movement begins.

    9. The argument in one view

    Stripped of its polemical edges, the paper can be summarized as a five-part argument.

    Macroeconomic time series can be highly persistent. Treating every recession as a temporary deviation from an invariant trend is therefore an empirical assumption, not a statistical law.
    Some major shocks leave permanent output losses. The post-crisis economy may grow again without recovering the level it would otherwise have reached.
    Profitability is central to capitalist investment. The evidence reviewed in the paper indicates that profits possess substantial predictive power for subsequent investment.
    The average rate of profit exhibits a historical tendency. The Marxian studies cited by Gómez Julián interpret long-run profitability data as showing a secular downward movement interrupted by cyclical recoveries and counter-movements.
    The economy therefore has memory. If profitability conditions accumulation and crises alter the subsequent path, capitalist development should be modeled as a historical process in which past states help create future ones.

    That final proposition is the most intellectually interesting part of Gómez Julián’s essay. The significance of non-stationarity is not that a statistical test can settle a two-century debate in political economy. It is that the statistical language of permanent shocks, stochastic trends and path dependence is difficult to reconcile with a simplistic image of economic history as temporary noise around an eternally self-restoring equilibrium.

    Marx’s falling rate of profit and the unit-root literature are not the same theory, and one does not mechanically prove the other. But they meet around a common challenge: what if the economic system carries its own history forward?

    Once that possibility is admitted, a crisis is not merely something that happens to an otherwise unchanged economy. It becomes one of the events through which the economy itself is historically made.

    · · ·

    Conclusion: taking history seriously

    The paper begins with an econometric distinction but ends with a claim about the nature of political economy. Stationarity describes a world capable, under appropriate conditions, of forgetting. Unit-root behavior describes a world in which disturbances can survive inside the future.

    Gómez Julián argues that the second image is more compatible with the historical character of capitalist development and with Marx’s analysis of accumulation. The evidence on permanent output losses challenges easy assumptions of automatic restoration; the evidence on profits and investment gives profitability a mechanism through which it can shape the real economy; and the cited long-run profit-rate estimates provide the directional component required for the Marxian argument.

    The technically careful conclusion is therefore stronger when stated modestly. Unit roots do not demonstrate the falling rate of profit. What they undermine is the presumption that economic disturbances must disappear without changing the long-run path. Once persistence is combined with evidence about the historical movement of profitability and its relationship to accumulation, the paper’s central thesis comes into view.

    The deepest question is not whether an economy eventually grows again. It is whether, after history has happened, the old path still exists to be returned to.
    Principal works discussed in the paper

    Campbell, J. Y. & Mankiw, N. G. (1987). Are Output Fluctuations Transitory?

    Blanchard, O. (2009). Sustaining a Global Recovery.

    Cushman, D. O. (2013). Paul Krugman Denies Having Concurred With an Administration Forecast: A Note.

    Kothari, S., Lewellen, J. & Warner, J. (2017). The Behavior of Aggregate Corporate Investment.

    Roberts, M. (2020). A World Rate of Profit: A New Approach and More on a World Rate of Profit.

    Tapia Granados, J. A. (2013). Does Investment Call the Tune? Empirical Evidence and Endogenous Theories of the Business Cycle.

    Read the Original Paper (In Spanish)
    EXPLANATORY ESSAY BASED ON JOSÉ MAURICIO GÓMEZ JULIÁN (2020) · UNIT ROOTS · NON-STATIONARITY · POLITICAL ECONOMY
  • The Shape of a Crisis: A General Theory of Capitalist Cycles

    The Shape of a Crisis: A General Theory of Capitalist Cycles

    Thesis Release · Political Economy

    The Shape of a Crisis

    A general theory of the cycles of the dynamics of the capitalist system in the long run — now available in English

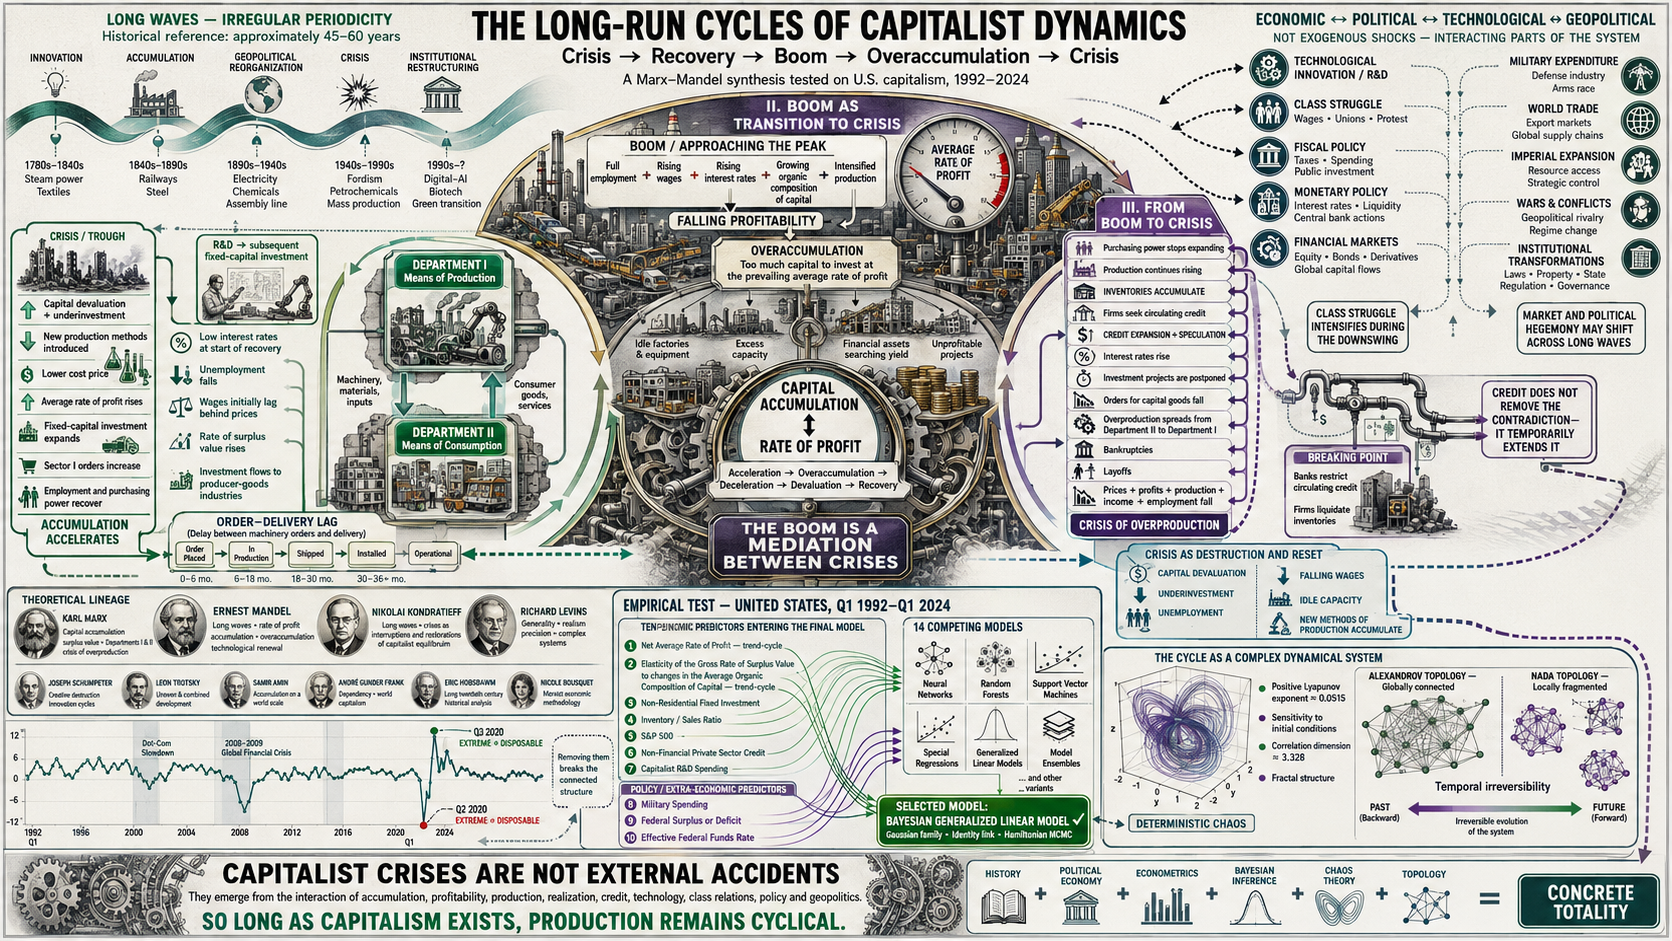
    Every few years the same story is told twice. First, that the economy has entered a new era in which the old rules no longer apply. Then, some months later, that what happened was an accident: a shock, a bubble, a virus, a war. Both tellings share a premise so quiet that it is rarely examined — that the rise and the fall are separate events, and that a good theory of the good years need not be a theory of the bad ones.

    The thesis released today argues the opposite, and then goes to some length to measure it. The boom and the crisis are not two phenomena but two moments of one: the crisis of overproduction is the mechanism by which capitalism restores the conditions of an accumulation that its own success had eroded. Devaluation clears the field; new methods of production are introduced under duress; profitability recovers on the ruins. The recovery is not the negation of the crisis. It is its product.

    That claim is old. What is new here is the attempt to make it decidable — to state it in a form that quarterly data on the United States economy between 1992 and 2024 could have contradicted, and then to check whether they do.

    Three questions, and why the order matters

    The investigation is organised around one general objective — to analyse the long-run cyclical behaviour of U.S. capitalism in the light of the dominant economic theories — and three specific ones, asked strictly in this order:

    • Which theory explains and predicts best? Not which is most elegant, or most widely taught, but which survives being pointed at the data.
    • Which factors generate the cycle? Economic and extra-economic alike — the thesis refuses in advance to treat wars and monetary policy as noise sitting outside a clean economic mechanism.
    • By which rules do those factors interact? A list of causes is not a theory. The theory is in the grammar that binds them.

    The order is not decorative. A great deal of applied economics answers the third question with machinery borrowed from a theory it never subjected to the first. Here the selection of the framework is itself a result, defended before it is used.

    Five families of an old argument

    Before measuring anything, the thesis maps the terrain. Economic thought on the cycle is sorted into five groups: the pre-Kondratieff non-heterodox schools; the Kondratieff school; the post-Kondratieff marginalist and neoclassical schools; the heterodox schools; and the historiographic vision of long waves, which reads the cycle through the archives rather than through the equations.

    With that map in hand, three long-running disputes are adjudicated rather than summarised. Does the crisis originate in overproduction or in underconsumption? Is a sustained expansion of credit a symptom of recovery, or of the exhaustion of the conditions that made recovery possible? Is there really an inverse relation between inflation and unemployment, or is the appearance of one an artefact of the precariousness of the labour market? Each is answered, and each answer carries consequences later, when the model is specified.

    A framework that states its own conditions of failure

    A substantial part of the theoretical apparatus is devoted to a materialist characterization of the dialectical method: its fundamental categories, a Marxist ontology built from a metalogical gnoseology, and an explicit treatment of verification, falsification and decidability. The purpose is unglamorous and indispensable — to fix, in advance, which propositions of the theory are empirically decidable and which are interpretive. Without that boundary, no amount of subsequent statistics can tell you what has been tested.

    Ten dials, seven of them internal

    The empirical core is a Bayesian generalized linear model of the growth of U.S. real output, estimated with Hamiltonian Monte Carlo and cross-validated against machine-learning and deep-learning competitors. It retains thirteen coefficients across ten factors. Seven are economic:

    FactorWhat it registers
    Net Average Rate of Profit (ARoP)The central variable of the accumulation process, and the one whose long-run tendency the theory predicts.
    Elasticity of the gross rate of surplus value to the average organic composition of capitalHow the exploitation of labour power responds when the technical structure of capital changes.
    Non-residential fixed investmentThe pace of accumulation in the productive sector; the hinge between boom and crisis.
    Inventory-to-sales ratioThe gap between producing value and realising it on the market.
    S&P 500Financialization, entering through a natural cubic spline with three degrees of freedom.
    Non-financial private sector creditThe credit system as the accelerator and the brake, splined with two degrees of freedom.
    Capitalist R&D spendingThe innovative impulse; the second largest coefficient in the model.

    And three are extra-economic: military spending (splined with three degrees of freedom), the federal surplus or deficit, and the effective federal funds rate. Their presence is not a concession to realism. It follows from the argument that an imperial economy counteracts the tendency of its own profit rate to fall by means that are not internal to its national accounts.

    The Average Rate of Profit carries the fourth largest coefficient of the thirteen — behind only the intercept, R&D spending, and one basis function of the splined S&P 500. The conclusion the author draws from its behaviour is worth quoting in substance: what is favourable to the global process of capital accumulation is not thereby favourable to the dynamics of aggregate growth. The two are not the same quantity, and treating them as one is precisely the confusion the cycle punishes.

    Note, too, what the splines are doing. Three of the ten factors would not sit still in a straight line. That is not a technical footnote: it is the first quantitative sign that the interaction of these factors involves thresholds and turning points rather than a stable proportionality.

    Not random. Chaotic.

    “Unpredictable” and “random” are not synonyms, and the difference decides what kind of science economics can be. A random system has no internal structure to find. A chaotic one is rigidly determined and still unpredictable at long horizons, because arbitrarily small differences in initial conditions grow exponentially apart.

    Three measurements place the U.S. economy in the second category. The Lyapunov exponent is positive (approximately $0.0515$): small perturbations amplify rather than dissipate. The correlation dimension is not an integer ($3.32798$): the attractor reconstructed by Takens’ theorem has a fractal structure, patterns repeating across scales of time and magnitude — which is what “cyclical, but not periodic” means when it is stated precisely. And recurrence quantification finds high determinism alongside variability in laminarity and in the maximum diagonal line length: underlying deterministic structures that themselves evolve.

    $\lambda > 0 \quad\text{with}\quad D_2 = 3.32798 \notin \mathbb{Z}$

    Read together, these say something a forecaster should find sobering and a theorist should find encouraging. The long-horizon forecast is not merely hard; it is structurally bounded. But the structure that bounds it is real, stable and measurable — which is exactly what a theory of the cycle needs to have something to explain.

    The shape of time

    The most unusual instrument in the thesis is topological. The idea is to stop asking how big the numbers are and start asking which observations can see which. Convert the series into a directed visibility graph — a link from one quarter to another when the second is visible from the first over the intervening data — and study the order structure that results.

    Two topologies are built on it, and they disagree in an informative way.

    • The coarser Alexandrov topology, built on temporal reachability, turns out to be connected. At the level of its order structure the economy is globally a single piece: every observation is bound to every other by chains of temporal visibility. There is no quarter that stands apart.
    • The finer Nada topology is locally fragmented — six components under the natural visibility graph, thirty-six under the horizontal one. Zoom in, and the fabric shows seams: structural discontinuities at the level of closed neighbourhoods.

    Global unity and local rupture at once. That duality is not a contradiction to be resolved; it is the object being described. And a third measurement gives the whole thing a direction: the bitopological analysis yields $D = +4$, meaning that expansions generate more temporal visibility than contractions. The cycle is not symmetric in time. Growth accumulates gradually and in view; collapse happens abruptly and blind. Run the film backwards and it is recognisably the wrong film.

    ⚠️ Why you must not “clean” the crises

    There is a habit in applied work of treating extreme values as contamination and smoothing them away by discontinuous imputation. Here that habit is shown to be a category error with a measurable price. The extreme fluctuations of the 2020 crisis belong to a connected block even under the finer topology; severing them is a topological rupture, not a cleaning operation. The thesis reports the consequence directly: models fitted after such imputation performed worse, because one was using predictors suited to one phenomenon — real output growth — to predict a qualitatively different one: real output growth after the crisis had been removed from it. The crises are not noise around the cycle. They are the cycle.

    The grammar of the cycle

    The third question receives a seven-part answer. The factors interact through feedback (the rate of profit shapes investment, investment shapes the organic composition of capital, which feeds back into the rate of profit); time lags (R&D and fixed investment pay out on a delay, and the delay is itself cycle-generating); non-linearity (thresholds and regime changes, which is why three factors needed splines); deterministic chaos; sectoral interdependence between the department producing means of production and the one producing means of consumption; topological structure, global connectedness with local fragmentation; and the influence of the global context, which is how military spending and the S&P 500 enter a nominally domestic account.

    The unifying claim is that each phase of the cycle contains the seed of its own negation. New methods of production introduced during the crisis lay the foundations of the next boom; the overaccumulation of the boom prepares the ground for the next crisis. Innovation initially arrests the fall of the profit rate and ultimately deepens it — through the way the degree of exploitation of labour power responds, over time, to the very methods introduced to raise it.

    What a cycle is for

    The thesis closes on a question most treatments never pose. If the cycle is a mechanism, what does it accomplish? Two answers, at different depths. Its intermediate practical end is to restart the process of capital accumulation once instability has reached a critical level — this the mechanism achieves, repeatedly, at a cost borne unevenly. Its definitive practical end is to lay the material and spiritual conditions for a reorganization of the fundamental productive structure of society, one capable of a stability beyond what the capitalist mode of production can reach within its own limits.

    What this establishes, and what it does not

    The evidence supports the claim that classical Marxist economic theory possesses the greatest explanatory and predictive capacity for long-run cycles among the theories examined here, on this economy, over this period. It is a comparative result on the United States between 1992 and 2024, quarterly — not a universal proof, and not a forecast. The thesis is explicit about the cost of its own data: the Average Rate of Profit and the average rate of surplus value were available only annually through 2020, and completing the series to 2024 required temporal disaggregation and prediction, which puts a wider band of uncertainty around the most recent quarters. The philosophical, historical, conceptual and statistical scope of each result is distinguished in the text, and results unfavourable to the hypotheses are reported alongside the favourable ones.

    About this edition

    This is the English edition of a thesis originally written in Spanish and submitted to the Universidad Latina de Costa Rica for the degree of Licentiate in Economics. It is interdisciplinary by construction, drawing on Marxist political economy, dialectical and historical materialism, the history and historiography of economic thought, the philosophy and methodology of science, econometrics, Bayesian statistics, the theory of complex systems and topology.

    The edition carries a Note on the Translation that fixes the rendering of the terms whose Spanish usage is technical and not interchangeable with their nearest English cognates — gnoseology, sublation, long wave, solvent demand, technique — and records the editions from which quotations are taken, including the two distinct English and Spanish editions of the Soviet philosophical dictionary, which are cited under different transliterations because they are different books with different pagination.

  • CAPITAL ACCUMULATION THROUGH DISPOSSESSION OF INDIGENOUS PEOPLE IN COSTA RICA

    CAPITAL ACCUMULATION THROUGH DISPOSSESSION OF INDIGENOUS PEOPLE IN COSTA RICA

    Costa Rica’s Democratic Myth: How Indigenous Dispossession Built the Country’s Agrarian Wealth
    Reading Notes · Political Economy · Latin American History

    Costa Rica’s Democratic Myth:
    How Indigenous Dispossession
    Built the Country’s Agrarian Wealth

    A plain-language reading of a groundbreaking study that dismantles the “White Legend” — and asks why a “democratic” state systematically violates the very rights it claims to protect.

    Based on: Gómez Julián, J. M. (2026). Revista de Historia, N.º 93, pp. 1–45.

    Costa Rica likes to think of itself as the exception. A small, peaceful republic nestled between two oceans, crowned with universal healthcare, no army since 1948, and a democratic tradition so stable that political scientists have called it the “Switzerland of Central America.” This flattering self-image — what scholars have long called the “White Legend” (Leyenda Blanca) — is one of the most durable stories in Latin American politics. It is also, according to a meticulous new study by Costa Rican economist José Mauricio Gómez Julián, profoundly misleading.

    Published in the Revista de Historia (University of Costa Rica, No. 93, 2026), the article sets out to do something ambitious: not merely to describe the well-documented inequality in Costa Rican land ownership — earlier scholars had already done that — but to explain why a formally democratic state produces, protects, and reproduces extreme agrarian concentration, generation after generation, and why the systematic violation of indigenous territorial rights is not an unfortunate glitch in the system but one of its operating mechanisms.

    The answer, the author argues, lies in understanding land dispossession not as a historical accident but as a structural feature of capital accumulation — a process that began with Spanish colonialism, was formalized by the liberal republic, was turbocharged by coffee and banana exports, and continues today under the twin guises of “conservation” and legal impunity.

    0.7258
    Gini coefficient for land concentration in Costa Rica’s southern region (Coto Brus). For context: 0 means perfect equality, 1 means one person owns everything. Sweden’s is around 0.53.

    The Numbers Behind the Myth

    Before we get to history, let’s sit with some uncomfortable statistics — the kind that rarely appear in Costa Rica’s tourism brochures.

    The Gini coefficient — the standard measure of inequality, where 0 is perfect equality and 1 is total concentration — tells a stark story. In Costa Rica’s southern region, land concentration reaches 0.7258. In Guanacaste’s cattle ranches, it climbs as high as 0.9. Nationally, the figure hovers around 0.796. For perspective: the top 1% of farms holds more than 37% of all agricultural land, while the bottom 39% of farms collectively own just 0.2%.

    And the people who work the land? Between two-thirds and three-quarters of Costa Rica’s agricultural workforce is landless — a proportion higher than anywhere else in Central America. In some regions like Coto Brus, more than 90% of farms lack legal titles.

    These figures are not from a radical pamphlet. They come from rigorous academic work by scholars like Mitchell Seligson, Marc Edelman, Charles Brockett, Jeffery Paige, and James Dunkerley — researchers who compared census data with actual property records and found that the state’s own statistics systematically underestimate the degree of concentration. Gómez Julián builds on their empirical foundation but adds a layer they largely did not: a categorical political-economic explanation of why this pattern persists within a formally democratic state.

    “Nearly three-quarters of the Costa Rican peasantry today are landless” — a fact that contradicts the national story of a country of small, equal farmers.

    A Timeline of Dispossession: From Encomienda to Enclave

    The article reconstructs the history of indigenous land loss in Costa Rica across five major phases. Each one reveals a different mechanism, but all serve the same structural function: clearing land and resources for capital accumulation.

    1. Colonial Foundations (pre-1821)

    Spanish conquest introduced three key instruments of dispossession: encomiendas (assigning indigenous labor to settlers), reducciones (forced resettlement into concentrated villages), and composiciones fraudulentas (legal maneuvers to convert indigenous land into colonial property). Roman law justified the entire operation by declaring indigenous lands to be property of the Spanish Crown. Though later laws like the Leyes Nuevas of 1542 formally attempted to protect indigenous peoples, the legislation on “vacant lands” (baldíos) declared as empty the very territories where indigenous communities lived, making them available for non-indigenous appropriation. By the end of the colonial period, a fragile but real legal recognition of “indigenous property” still existed through reducciones and “indigenous neighborhoods.” This legal floor is precisely what the post-colonial liberal state would systematically dismantle.

    2. The Liberal Republic Strikes (1821–1880)

    Independence did not bring recognition — it accelerated dispossession. In 1841, under the dictatorship of Braulio Carrillo, the Código General formally abolished the communal indigenous land regime as a protected legal category. Then, in 1882, Presidential Decree No. XIV declared vast stretches of northern territory — including the homeland of the Maleku people (historically called “Guatuso”) — to be baldíos: vacant state land open to appropriation by non-indigenous settlers and ranchers. The Maleku suffered what the article describes as one of the most intense proportional territorial and demographic reductions in Costa Rican indigenous history.

    1841
    Year the Código General, under dictator Braulio Carrillo, formally abolished communal indigenous land tenure — legalizing de facto what colonial expansion had already done.

    3. Coffee, the Beneficio, and Silent Proletarianization (1830–1930)

    The coffee boom created Costa Rica’s agrarian structure — and its contradictions. Unlike Guatemala or El Salvador, Costa Rica did not develop enormous haciendas. The largest farm was 604 hectares; the average was 41. By 1963, 58.5% of cultivated land was in units smaller than 35 hectares. This is the image the “White Legend” celebrates: a nation of smallholders.

    But the fine print tells a different story. Over 70% of the rural population was landless — a higher proportion than anywhere else in Central America. Power concentrated not through land-grabbing alone but through the beneficio (coffee-processing mill): in 1850, just sixteen beneficios controlled 85% of coffee exports, and access to the beneficio determined a small producer’s ability to finance and sell their crop. Credit systems tied small producers to merchant-landowners in relationships of dependency. Land prices inflated roughly twenty-fold in thirty years, incentivizing small producers to sell their parcels and then sell their labor.

    Critically, the Huetar people of Orosí resisted the coffee frontier around 1860 — an episode largely absent from standard histories of the coffee cycle. The “virtual absence of indigenous population” in the Central Valley during the great coffee expansion, which Dunkerley cited as one factor explaining Costa Rica’s distinct political development, was not a pre-existing geographic condition. It was, the article argues, the result of colonial epidemics (severe die-offs between 1576 and 1581), the legal dissolution of communal landholding in the 19th century, and physical displacement in the face of the advancing coffee frontier.

    4. Bananas, the Atlantic Enclave, and the Displacement of the Bribri and Cabécar (1870–1940)

    On Costa Rica’s Caribbean side, a parallel story unfolded — this one driven by foreign capital. The Soto-Keith Contract of 1883 granted Minor Keith 800,000 acres of state land, a 99-year railway lease, and sweeping tax exemptions. By 1890, his operation was the largest banana producer on Earth. The standard narrative presents this as development on “vacant land.”

    It was not. The Bribri and Cabécar peoples who inhabited the Talamanca valley were forced to move inland, deeper into their ancestral territory, because the banana concession included a significant portion of indigenous lands along the Sixaola river basin. The article calls this one of the key regional mediations of the dispossession process: the banana enclave was not merely a deal between a state and a transnational — it was a concrete mechanism of indigenous dispossession, legally articulated through the fiction of the baldío and materially executed through corporate control of Caribbean space.

    The United Fruit Company (UFCO) would later reduce its Atlantic plantations, face a major strike in 1934, and eventually shift production to the Pacific after the sigatoka disease devastated crops in 1938. But the damage was done: the “absence of indigenous population” in banana-region analyses reproduces, with different words, the same ideological device that operates in the coffee narrative — it naturalizes absence by hiding the dispossession that produced it.

    5. Limited Reform, Titulación, and the Persistence of Inequality (1957–1990)

    Costa Rica did attempt reform. International Convention 107 of the ILO (approved domestically in 1959) recognized indigenous and tribal peoples’ rights. Law 2825 of 1961 repealed the baldíos framework and declared such lands “state property” grounded in the social function of ownership. The Indigenous Law of 1977 (Law 6172) reserved portions of territory for indigenous peoples and granted full legal capacity to their communities through Asociaciones de Desarrollo Integral (ADIs).

    Yet the contradictions were glaring. The 1961 law allowed expropriation of idle land but required cash payment at market value — a provision that severely limited implementation. By 1970, only 1,272 families had been settled on roughly 35,400 hectares. The titling program backed by USAID reached a partial result of about 20,462 titles (some 339,761 hectares) by September 1979, at a rate of 425 titles per month against a theoretical capacity of 900–1,000.

    The results were telling. After receiving a title, the proportion of beneficiaries with access to credit rose from 18% to 31.7% — but the Gini coefficient for titled land was about 0.708, and when all land possessed by beneficiaries (titled plus other holdings) was included, it rose to nearly 0.781, almost identical to the national figure. Titling did not correct structural inequality — it potentially consolidated it. As the article puts it: these programs reached only a fraction of landless families while maintaining the fundamental structures of concentration.

    “Titling does not correct structural inequality and may consolidate it.”

    Conservation as Dispossession: The Modern Face of an Old Story

    One of the most striking arguments in the article is that the Costa Rican state itself — not just private ranchers or transnational corporations — has become a primary agent of indigenous dispossession, and it has done so wearing the respectable clothes of environmentalism.

    In 1982, Costa Rica created the Parque Internacional La Amistad (PILA), which was recognized as a UNESCO Biosphere Reserve that same year and as a World Heritage Site in 1983. What the celebratory narrative omits is that the park appropriated, as state-managed protected area, significant extensions of ancestral territory claimed by the Bribri and Cabécar peoples — without prior, free, and informed consultation. Its buffer zone includes the indigenous territories of Ujarrás, Salitre, and Cabagra. Inside the Biosphere Reserve, sixteen indigenous territories of five different peoples are situated. The state thus re-emerged, in this phase, as the principal agent of dispossession, this time through the legal figure of conservation.

    A similar dynamic operates through the Pago por Servicios Ambientales (PSA) — Costa Rica’s flagship Payment for Environmental Services program, administered by FONAFIFO. As documented by researcher Vargas Mena, the PSA has operated inside officially recognized indigenous territories. The forest, the water, and even the air (in the form of the carbon market) are commodified as “environmental services” whose monetary yield flows out of indigenous territory or is captured through institutional mechanisms that subordinate community decisions to the timelines and requirements of external agencies. This is not, the article argues, a correction of agrarian capitalism — it is a new phase of it.

    Add to this the contemporary presence of pineapple and palm oil multinationals in the southern zone, whose expansion encroaches on Bróráni, Bribri, and Cabécar territories. Their externalities — intensive water use, agrochemical contamination, pressure on adjacent lands — operate as mechanisms of environmental and economic dispossession on indigenous communities.

    16
    Indigenous territories of five different peoples situated inside the PILA Biosphere Reserve — appropriated without prior, free, and informed consultation.

    Recovering What Was Lost — and Dying for It (2011–Present)

    Faced with the persistent failure of the state to enforce legally recognized rights, indigenous movements launched what they call recuperaciones de facto: community-led recoveries of territories formally inscribed under the ADIs but materially usurped by non-indigenous occupants. Beginning in 2011 in places like Salitre, Cabagra, and Térraba, these recoveries triggered the organized, violent reaction of ranchers determined to suppress them.

    The consequences have been lethal. On March 18, 2019, Bribri leader Sergio Rojas Ortiz was assassinated. On February 24, 2020, Brórán leader Jethy Rivera was killed. Both murders occurred despite the existence of precautionary measures from the Inter-American Commission on Human Rights (Measure 321-12, issued in 2015). The impunity has been near-total: the Rojas case was archived in January 2024 with no detained suspects. In the Rivera case, the material perpetrator was initially convicted in February 2023, but the appellate court in Cartago reversed that conviction in July 2023, and in a second trial in August–September 2024, the accused was acquitted — despite his confession — under the principle of in dubio pro reo.

    The UN Special Rapporteur on the Rights of Indigenous Peoples documented that these attacks remain unpunished, with Costa Rican authorities failing to investigate even when perpetrators are known to the community. The cycle of dispossession–resistance–repression, the article argues, reveals that the de facto recoveries are not isolated incidents but the empirical manifestation of an ongoing class struggle over the means of production, mediated by a persistent colonial condition.

    “The contemporary accumulation by dispossession requires the same extra-economic violence that Marx identified in primitive accumulation.”

    A Broader Pattern: The State Always Chooses Sides

    The indigenous story does not exist in isolation. The article places it within a broader pattern of how the Costa Rican state has responded to rural land conflicts throughout its modern history — and the answer is consistent: it favors capital.

    The 1983 crisis is emblematic. When United Brands announced it was leaving, the state bought its land at $35,000 per hectare — a price that demonstrated the state’s weakness vis-à-vis transnationals. Standard Fruit demanded $200 million in credits and fired 700 workers. In the first eighteen months of the Monge administration alone, 185 rural conflicts were registered. In July 1983, 3,500 hectares of United Brands land were occupied by union militants and campesino federation members — and they were evicted by 600 police officers.

    Land occupations surged across administrations: 70 under Trejos, 500 during the Figueres (second) and Oduber governments, 120 in Carazo’s first year alone. The “land question” was never limited to Guanacaste, where cattle-ranching concentration had always been extreme and conflictive — it was a national structural feature.

    Rebuilding Political Categories from the Ground Up

    Here is where the article makes its most ambitious theoretical move. Rather than importing Marxist categories as ready-made tools, Gómez Julián claims to reconstruct them inductively from the historical evidence itself. The sequence is deliberate: facts first, categories second, return to facts with new interpretive power third.

    The State, in class societies, is the social organization of the political power of the economically dominant class. Law is the system of enforceable norms established by state power — it is the legal organization of that political power. Government is the administration of state institutions, and crucially, the economically dominant class is not necessarily the governing class: those who hold power are not always those who administer it, but the governing class is factually subordinate to the dominant class.

    Democracy, in its most general sense, is the government of the majority over the minority. But this concept was coined in slave-owning Athens of the 5th century BC, where only adult male citizens could vote, excluding women, slaves, and foreigners. The democracy of adult male citizens was a dictatorship for everyone else — the overwhelming majority. This dialectical relationship extends to all class societies: every democracy is a dictatorship for those systematically excluded from the majority’s will, and every dictatorship preserves an internal “democracy” for the class that imposes its hegemony. The relationship is dialectical, not identical.

    The Rule of Law (Estado de Derecho) is the idea that the state’s power is regulated and guaranteed by law — meaning the state creates law and then voluntarily submits to its own creation. But the article argues this is a sophism: states do not create law to submit to it; they create it as a regulatory framework founded on the interests of the politically and ideologically dominant class. As evidence, the author points to Article 105 of Costa Rica’s own Constitution, which prohibits referendums on budgetary, tax, fiscal, monetary, credit, pension, security, and administrative matters — that is, on virtually every fundamental issue of national social life. The validity of any referendum result is ultimately subject to the decision of the Legislative Assembly. The state, in other words, has structurally exempted itself from popular will on every matter that counts.

    And corruption? It is not an aberration. Defined as the practice in which a public official formally deviates from the functions for which they were entrusted with power, corruption “formally” (not factually) departs from stated commitments. Why is the deviation formal rather than factual? Because, within this framework, corruption is a necessary mechanism for the interests of the dominant class to impose themselves over the rest of society while electoral democracy reigns — one of several mechanisms that enable factual dictatorship through the alienation of the dominated classes.

    Three Processes, Two Levels of Abstraction

    The theoretical heart of the article lies in the way it reconstructs the relation among primitive accumulation, accumulation by dispossession, and what it calls acumulación entrelazada. In this post, I translate the latter deliberately as intertwined accumulation. The choice matters because it allows us to distinguish the concrete process reconstructed in the Costa Rican case from the broader concept of entangled accumulation developed by Guilherme Leite Gonçalves and Sérgio Costa.

    The distinction is not merely terminological. At the level of objective historical processes, primitive accumulation and accumulation by dispossession can possess relative autonomy: they are distinguishable mechanisms with their own immediate forms, temporal locations, and material effects. Relative autonomy does not mean isolation. It means that one can identify each process in reality without denying that, under concrete historical conditions, they coexist, penetrate one another, and alter the conditions under which the other operates.

    Primitive Accumulation

    Marx’s original problem: the violent historical separation of producers from their means of production and the construction of the property relations required for capitalist production. In the Costa Rican sequence, this includes colonial dispossession, Carrillo’s 1841 abolition of communal tenure, the 1882 decree that treated Maleku territory as vacant land, and the Soto-Keith concession of 1883. These are not simply old events remembered by a later capitalism; they establish legal and material conditions that subsequent accumulation inherits.

    Accumulation by Dispossession

    David Harvey’s formulation identifies the continuing and contemporary use of expropriatory practices: privatization of land and common goods, suppression of collective rights, commodification of previously non-commodified spheres, colonial or neo-colonial appropriation of assets, and the use of credit, law, and state power to transfer resources. In the Costa Rican case, this logic appears in contemporary territorial occupation, conservationist appropriation, environmental-service markets, and other mechanisms that convert collectively preserved resources into fields of accumulation.

    Intertwined Accumulation

    As reconstructed here from Gómez Julián’s Costa Rican case, intertwined accumulation names the concrete relation of mutual conditioning and reinforcement among relatively distinguishable accumulation processes. It is the point at which an earlier expropriation creates the legal, spatial, or social conditions for a later dispossession; the later dispossession reproduces or deepens the effects of the earlier one; and both become connected to new fractions of capital, state institutions, and wider circuits of accumulation. In this sense, intertwined accumulation is not a synonym for either primitive accumulation or accumulation by dispossession, nor does it abolish their analytical distinction.

    Relative Autonomy Does Not Mean Separation

    This way of reading the historical record avoids a false choice. We do not need to say either that primitive accumulation is a closed episode belonging only to the birth of capitalism, or that every later dispossession is simply the same phenomenon under a new name. A concrete process may be identified as primitive accumulation when it restructures property relations by separating communities from the conditions of their reproduction. A contemporary process may be identified as accumulation by dispossession when already existing rights, assets, commons, or public resources are transferred into circuits of capital. And a third analytical problem appears when the effects of these processes become causally linked.

    That third problem is what intertwined accumulation captures here. The relevant relation is not merely chronological succession. It is a material interaction: one process changes the conditions of possibility of another. Earlier legal destruction of communal tenure can make later private occupation easier; later occupation can normalize and reproduce the property regime created by the earlier rupture; state regulation can connect both to transnational commodity chains, tourism, conservation finance, or carbon markets. The processes remain distinguishable, but their effects are no longer additive. They become synergistic.

    Concrete analytical structure
    Primitive accumulation + accumulation by dispossession → mutual conditioning → intertwined accumulation

    The arrow does not mean a rigid historical sequence. It represents a causal relation that may operate across different periods, regions, and institutional forms.

    The Costa Rican mapping makes this visible. Carrillo’s abolition of communal tenure created a legal environment within which the Huetar coffee-frontier dispossession could advance. Decree XIV of 1882 converted Maleku territory into legally available space and enabled its appropriation by ranchers and settlers. The Soto-Keith concession connected territorial dispossession in Talamanca to transnational banana capital. PILA and the PSA later inserted ancestral territory into conservationist and environmental-value circuits, linking local territorial conflict to tourism, state administration, and global carbon capital. The post-2011 de facto recoveries reveal the contemporary collision between the collective indigenous regime and the individual capitalist regime produced through this long history.

    Entangled Accumulation: The Broader Category

    This is where Gonçalves and Costa’s concept of entangled accumulation becomes especially useful. Their 2019 formulation is deliberately broader. It seeks a comprehensive category for the interdependencies that have structured capitalist expansion across history: exploitation and expropriation; wage and slave or otherwise unfree labor; state power and illegal violence; capitalist and non-capitalist economies; different geographical scales; different historical periods; and intersecting social hierarchies such as class, race, ethnicity, and gender.

    In that broader framework, primitive accumulation, accumulation by dispossession, financial expropriation, superexploitation, and other forms do not follow a rigid chronology. They may coexist in the same period and space, disappear and re-emerge, and become connected through law, politics, corruption, culture, discourse, and the changing boundary between state and market. Entangled accumulation therefore operates at a higher level of abstraction: it is a general category for the historical interpenetration of multiple mechanisms and dimensions of capitalist accumulation.

    The two concepts can therefore be related without collapsing them into one another. Intertwined accumulation, as used in this post to interpret the Costa Rican article, is the more concrete category: it identifies a specific process of causal articulation and synergy among distinguishable modes of accumulation inside a determinate historical formation. Entangled accumulation, in Gonçalves and Costa’s sense, is the more general category under which such concrete articulations can be theorized together with many other forms of interdependence.

    Relationship between the concepts
    EintertwinedEentangled

    This set-theoretic expression is an interpretive shorthand used in this post, not a formula stated verbatim by either paper. It means that the specific Costa Rican process can be treated as one concrete determination within the wider family of interdependencies captured by entangled accumulation.

    This distinction also clarifies why the Costa Rican article can speak of the convergence of primitive accumulation, accumulation by dispossession, and intertwined accumulation without reducing all three to one undifferentiated process. The first two refer to mechanisms that can be identified with relative autonomy; the third refers to their concrete articulation when they coexist and reinforce one another. At the same time, that entire configuration can be located within Gonçalves and Costa’s more encompassing theory of entangled accumulation. What looks like a terminological inconsistency at a purely abstract level thus becomes, at the level of historical reality, a useful distinction between mechanisms, their interaction, and the general category capable of containing both.

    The key distinction is between a mechanism and a relation among mechanisms: primitive accumulation and accumulation by dispossession can be identified separately, while intertwined accumulation names the historically concrete synergy through which they condition and reproduce one another.

    A Timeline of Dispossession: Key Milestones

    1542–1880

    Laws on baldíos, early decrees (e.g., Guatuso). Legal-administrative dispossession: Crown → State → Private hands.

    1830–1890

    Coffee boom and beneficio system. Concentration via processing and credit. Huetar resistance in Orosí (c. 1860). Dissolution of communal land regime.

    1870–1910

    Banana concessions (Keith/UFCO). Bribri-Cabécar displacement. Atlantic enclave; corporate spatial control; dispossession in Sixaola.

    1933–1940

    Coffee regulatory bodies (Instituto de Defensa del Café). Crisis management without reversal of concentration.

    1950s–1970s

    Internal colonization (ITCO/IDA). Convention 107. Law 2825. Partial titling; insecurity and frontier appropriations persist.

    1977

    Indigenous Law 6172. Formal recognition vs. persistent non-indigenous occupation.

    1982

    Creation of Parque Internacional La Amistad (PILA). State-conservationist appropriation of Bribri-Cabécar ancestral territory.

    2011–present

    De facto recoveries in Salitre, Cabagra, Térraba. Community reoccupation. Threats and attacks intensify.

    2019–2024

    Assassinations: Sergio Rojas (March 18, 2019), Jethy Rivera (February 24, 2020). UN/IACHR: impunity. Rivera conviction reversed; Rojas case archived.

    Why Land Is Not Just Land: The Question of Rent

    The article introduces one more theoretical tool that deserves attention: the Marxist concept of ground rent — both natural and differential. Contemporary indigenous struggles, the author argues, cannot be explained solely by the seizure of land as a means of production. They also revolve around the natural resources those lands contain: water, forests, biodiversity, scenic beauty, carbon sequestration capacity. The yield from these resources can be converted into rent that is appropriable by various fractions of capital — agroindustrial, extractivist, touristic, conservationist (private or state-run).

    The PSA inside indigenous territories, the nature tourism surrounding national parks created on ancestral lands, the monetization of environmental services in the carbon market, and adjacent agroindustry are all concrete devices through which capital captures or redistributes rents whose material base is precisely the territories that indigenous peoples have preserved through their historical struggle. Indigenous territorial defense is therefore simultaneously defense of communal use-value against capitalist exchange-value, and a material obstacle to the full realization of differential rent by capital.

    What This Means — and Why It Matters Beyond Costa Rica

    The article’s conclusions are blunt. The “White Legend” of Costa Rican democratic exceptionalism does not survive contact with the evidence. A country where nearly three-quarters of the peasantry is landless, where the Gini coefficient for land ownership approaches 0.8 nationally and reaches 0.9 in cattle regions, where over 90% of farms in some zones lack legal titles, and where indigenous leaders are assassinated with impunity for reclaiming territories that the state itself has legally recognized as theirs — that country is not a democratic anomaly in an unequal region. It is a case study in how formal democracy and extreme agrarian concentration coexist, and how the latter is structurally enabled by the former.

    The argument is not that Costa Rica is uniquely evil. It is that the myth of its exceptionalism serves a function: it legitimizes the very regime of accumulation that makes extreme inequality possible. The “White Legend” is not a miscalculation or a public-relations excess. It is, in the article’s framework, an ideological device that is functional to the system it obscures. As long as Costa Rica believes it is democratic and equal, the structural mechanisms that produce dispossession operate without scrutiny.

    And the final, perhaps most unsettling implication: the article concludes that non-indigenous civil society participation is essential to defend rights that are “fundamentally irreconcilable with the needs of accumulation.” The rights of indigenous peoples over their territories, in other words, cannot be secured within the existing accumulation regime without a political rupture that extends beyond indigenous communities alone. This is not a call for charity or solidarity in the conventional sense. It is a structural observation: the system that dispossesses indigenous peoples is the same system that produces landlessness among non-indigenous peasants, and their interests converge at the point where the logic of accumulation is challenged.

    §

    A Note on the Source

    This post is primarily a reading of José Mauricio Gómez Julián, “Acumulación por despojo y el mito del excepcionalismo democrático costarricense: el despojo indígena como rasgo estructural de la concentración agraria,” Revista de Historia, No. 93 (January–June 2026), pp. 1–45, published by the Universidad Nacional de Costa Rica. The article is available under a Creative Commons Attribution-NonCommercial-ShareAlike 4.0 International license. The author is an independent researcher specializing in political economy and statistical methodology, with a degree in Economics from the Universidad Latina de Costa Rica.

    The conceptual clarification developed above also engages Guilherme Leite Gonçalves and Sérgio Costa, “From primitive accumulation to entangled accumulation: Decentring Marxist Theory of capitalist expansion,” European Journal of Social Theory (2019), DOI 10.1177/1368431018825064. To keep the analytical levels distinct, this post deliberately reserves entangled accumulation for Gonçalves and Costa’s broad category and uses intertwined accumulation for the more concrete process reconstructed from the Costa Rican case. That terminological distinction is an interpretive choice of this post rather than a claim that the two papers themselves explicitly establish the same hierarchy in those exact words.

    The article is explicitly situated within Marxist political economy and historical materialism. It does not claim neutrality: it argues that the theoretical framework it employs has superior explanatory power for the phenomena it documents, and it reconstructs its core political categories (State, Law, Democracy, Rule of Law, Corruption) inductively from the historical evidence rather than importing them as axioms. Readers who disagree with the theoretical framework may still find the empirical documentation — drawn from census data, property records, legislation, UN reports, Inter-American Commission records, and direct indigenous testimony — valuable in its own right.

    The data referenced throughout — Gini coefficients, titling statistics, acreage figures, occupation percentages — are drawn from the sources the article cites (Seligson, Edelman, Brockett, Dunkerley, Paige, Guevara and Chacón, Vargas Mena, Zúñiga et al., and others). No figures have been invented or extrapolated beyond what the article itself presents.

    “The history of the communities indigenous from the conquest to the present reveals not an exceptional democratic inclusion but a systematic dispossession as a structural feature of capital accumulation.”

  • SOME REFLECTIONS ON MARX’S PRICES OF PRODUCTION

    SOME REFLECTIONS ON MARX’S PRICES OF PRODUCTION

    Was Marx Wrong About Prices of Production? — A 260-Page Investigation Says No

    Political Economy • Econometrics • Marx

    Was Marx Wrong About Prices of Production?
    A 260-Page Investigation Says No.

    How one researcher spent years showing that the most famous critique of Marx’s economics rests on a mistake Marx never made.

    Based on: Gómez Julián (2026), “Some Reflections on Marx’s Prices of Production” — Introduction, Conclusions & the Formal-Empirical Chapter · DOI 10.5281/zenodo.21842251

    A Fatal Flaw, or a Fatal Misreading?

    For over a century, a single mathematical argument has been wielded as the definitive proof that Karl Marx’s economics doesn’t work. It goes like this: Marx claimed that the value of goods is determined by the labor that produces them, and that market prices eventually gravitate toward “prices of production” — modified versions of those labor values, adjusted for how capital-intensive each industry is. But when you try to verify this with a system of simultaneous equations, the numbers don’t add up. The sums of values don’t equal the sums of prices. The theory, critics have said since the early 1900s, contains a fatal algebraic error.

    This paper — spanning 260 pages and drawing on philosophy, history, sociology, and statistics — argues that the error was never Marx’s. It was the error of the people who checked his math using a method he never used.

    The Photograph vs. the Movie

    Imagine you’re trying to understand a river. You could take a photograph of it — capturing one frozen moment — or you could film it as a movie, watching how the water flows over time. For over a hundred years, the economists who criticized Marx took a photograph of his theory and then complained that it didn’t look like a movie.

    Here’s the specific issue. Marx described a two-step process: first, a general rate of profit forms across the entire economy; then, each industry’s price deviates from its pure labor value according to how much capital it ties up relative to the average. The standard critique — originating with Ladislaus von Bortkiewicz in 1907 and repeated ever since — takes all of Marx’s accounting identities and solves them simultaneously, as if input prices and output prices were determined at the same instant. Under that framework, Marx’s three aggregate equalities cannot all hold at once.

    The “inconsistency” that has been attributed to Marx for over a century is the inconsistency of the simultaneous-dualist framework that was imposed on him, and it dissolves as soon as time is restored. — Gómez Julián, summarizing the central thesis

    But here’s the catch: solving everything simultaneously is equivalent to assuming that the economy is a photograph — that there is no time. And Marx’s entire framework is built on the opposite premise: that the economy is a process, an unfolding sequence in which the prices that exit one period become the input prices that enter the next. Once you restore that temporal dimension, the “inconsistency” vanishes. The three equalities hold simultaneously — not because Marx was secretly consistent in some miraculous way, but because the contradiction was an artifact of the framework imposed on him, not of his own logic.

    The paper calls the simultaneous approach “Walrasian Marxism” — a phrase that captures the irony: economists imported the logic of Léon Walras’s general equilibrium theory and used it to read Marx, then blamed Marx when the result didn’t work.

    In Plain Language

    Marx was accused for over a century of getting the arithmetic wrong. What actually happened is that someone redid his arithmetic under an assumption he never made — that the prices of things you buy to produce and the prices of things that come out of production are the same prices, set at the same time. If you assume that, Marx’s accounts don’t close. But that assumption is equivalent to saying the economy doesn’t happen in time.

    But Was the Movie Real?

    Pointing out that Marx’s logic works when you read it correctly is necessary but not sufficient. The “temporalist” school has been making this argument for nearly fifty years. But the author noticed a critical gap: nobody in that school had ever taken real-world data and actually estimated the three types of prices Marx described — direct labor values, prices of production, and market prices — and then tested whether market prices actually gravitate toward prices of production as the theory predicts.

    This matters because, as the paper puts it, leaving the correct reading of Marx “in the territory of conceptual argumentation while the incorrect reading occupies alone the territory of measurement” is a strategic vulnerability. If you can’t show that real prices behave the way your theory says they should, your theory remains a philosophical argument, however internally consistent.

    But before presenting any numbers, the paper devotes substantial space to establishing that the process Marx described actually happened in history. This is not an appendix; it’s a foundational part of the argument.

    Before Capitalism

    In pre-capitalist societies, exchange was regulated by labor time — not because someone enforced a theory, but because the material conditions made it so. Barter was dominant, inflation did not exist, and prices could only reflect production costs given available technology. Evidence from anthropology (Malinowski’s Trobriand Islands studies), sociology (Mauss on gift exchange), accounting history (Kula’s analysis of feudal estate records), and even paleogenomics all converge: objects were valued in proportion to the labor they embodied.

    The Transition

    The dissolution of feudal relations, the monetization of exchange, and the destruction of pre-industrial normative frameworks created the conditions for capital to move freely between industries. Thompson’s work on the “moral economy” documents how the new free-market ideology had to be violently imposed, destroying customary protections and creating an unprecedented relationship of exploitation.

    Capitalism Established

    Once barriers to capital movement were destroyed, capital flowed from commerce to industry chasing higher profits, and generalized competition forced a redistribution of total surplus value across sectors. The crisis of 1873 — which destroyed nearly half the blast furnaces in major iron-producing countries — is presented as concrete evidence of the mechanism: firms whose costs were still based on older, individually more labor-intensive methods went bankrupt when they couldn’t compete with prices of production dictated by modern technology.

    In Plain Language

    Prices of production didn’t appear the day someone wrote an equation. They appeared the day capital could freely move from one industry to another chasing the highest profit — which didn’t happen until legal, moral, and political barriers were destroyed. Before that, things were exchanged roughly according to the labor they cost, and there is more than enough evidence — ethnographic, accounting, archaeological, and genetic — to show it.

    What Is a Production Price, Exactly?

    This is where the paper moves into its most technically original territory. The author carefully separates two things that must not be confused:

    What a production price is (the explanandum): it is the expected value, over the distribution of economic perturbations, of the long-run time average of market prices. In plain language: it’s the center of gravity around which actual market prices keep spinning. Not the price they arrive at and stay at (that would be equilibrium), but the average around which they never stop oscillating.

    Key Concept

    The production price is neither an eternal, timeless equilibrium (the error of the simultaneous approach and of Walrasian economics, which takes the law as such for the whole and eliminates time) nor a chaos of prices without law (the error of empiricism, which stays at the level of individual prices and loses the law). It is the law of the whole realizing itself through the contingency of the parts.

    How each step of the process works (the explanans): a rule that determines this year’s market price from last year’s market price and last year’s latent production price, and nothing else. This is modeled as a hierarchical Ornstein-Uhlenbeck process — a three-level cascade in which the production price is itself a latent state with its own dynamic gravitating toward value, and market prices gravitate toward that latent state rather than toward a fixed, noisy index.

    The uncertainty is built into the model explicitly: uncertainty in the average rate of profit, uncertainty in the advanced capital, uncertainty in the disaggregation of national accounts into 37 sectors (handled through multiple imputation with 25 imputations combined by Rubin’s rule), and parametric uncertainty estimated through Bayesian Markov Chain Monte Carlo methods.

    One crucial point: no magnitude is obtained by solving a simultaneous system. Value is constructed empirically and directly as $V = c + v + p$ (cost plus surplus value), and production price as $\Phi = c + K \cdot G’$ (cost plus capital times the general rate of profit). There is no Leontief inversion, no simultaneous algebra, anywhere in the construction.

    In Plain Language

    Think of a production price as the “gravitational center” of a spinning object. The object (a market price) never stops moving — it wobbles, it swings, it drifts — but over time its average position is pulled toward that center. The math describes both what the center is and how each wobble happens, and it does so while honestly accounting for all the uncertainty in the measurement.

    The Defining Equations: (9) Through (11)

    Here is where the metaphor turns into mathematics. The paper writes the definition of a production price in three successive steps — each one making explicit an assumption the previous step left implicit — numbered (9), (10), and (11) in the original text. None of the three generates a trajectory by itself; together they define the explanandum — what the object is — that the cascade below then generates.

    Equation 9 — What a Production Price Is
    $$ \lim_{t\to\infty} E\!\left[\varphi^i_t\right] \;=\; k^i_t + K^i_t\, E\!\left[G'(t,X)\right] \;=\; \Phi^i_t $$

    Here $\varphi^i_t$ is sector i’s market price at time $t$, $k^i_t$ is its cost price (constant capital consumed plus variable capital), $K^i_t$ is the total capital advanced, and $G'(t,X)$ is the general rate of profit — itself a stochastic process indexed by a perturbation $X$ that bundles the exodus of capital between branches and technological innovation.

    In words: a production price is the long-run limit of the average market price. Not the price itself at any instant — that keeps oscillating forever — but where its time-average settles as the horizon stretches out. Notice the object on the right-hand side, $k + K \cdot E[G’]$: it is the same accounting identity introduced earlier (cost price plus the average profit rate applied to capital advanced), except the profit rate is now written as an expectation, because it fluctuates.

    Equation 10 — Making the Averaging Explicit
    $$ \Phi^i_t = \lim_{t\to\infty} E\!\left[\varphi^i_t\right] = \int_{-\infty}^{\infty} \!\left(\lim_{t\to\infty} \varphi^i_t(x)\right) f_X(x)\, dx \;=\; k^i_t + K^i_t \int_{-\infty}^{\infty} G'(t,x)\, f_X(x)\, dx $$

    $f_X$ is the probability density of $X$. The equation says the expectation is an average over every possible state $x$ of the system’s turbulence, weighted by how likely that state is.

    Equation (10) earns its keep by making a subtle move legitimate: swapping the order of the limit and the expectation. That looks harmless, but it hides a real question — does the market price $\varphi^i_t$ even converge to anything as $t \to \infty$? The paper’s answer is no: a capitalist system doesn’t settle into a fixed point, it settles into a limit cycle — perpetual oscillation. So the convergence the argument needs isn’t of the instantaneous price, but of its cumulative time-average. That average does converge, for almost every state of the world, precisely because the system is ergodic — the fraction of time the cycle spends in each region of its orbit stabilizes. This is the Birkhoff ergodic theorem doing, in mathematical language, exactly what Marx says in economic language: the production price isn’t the value the market price reaches and stays at, it is the average around which it never stops oscillating. The oscillation isn’t an obstacle to the average — it is the average’s condition of existence.

    Why the Order of Operations Matters

    The paper invokes Lebesgue’s Dominated Convergence Theorem to justify swapping “limit of the average” for “average of the limit.” This requires bounding market prices by some integrable envelope — economically, that no price can grow without limit, which technological ceilings and competitive pressure guarantee — and, crucially, it does not require that the convergence be uniform across sectors. Uniform convergence would mean competition equalizes profits instantly and identically everywhere, with no room for a shock to hit one industry harder than another. Marx’s theory says the opposite, and the math is built to allow it.

    Equation 11 — When the Capital Base Is Also Uncertain
    $$ \Phi^i_t = \lim_{t\to\infty} E\!\left[\varphi^i_t\right] = \int_{-\infty}^{\infty}\!\!\int_{-\infty}^{\infty} \left[k^i_t + K^i_t(y)\, G'(t,x)\right] f_{X\mid Y}(x\mid y)\, f_Y(y)\; dx\, dy $$

    Equation (10) still treated the capital base $K^i_t$ as known exactly. Equation (11) drops that simplification: $Y$ is a second random variable carrying the estimation error in $K$, with density $f_Y$, and $f_{X \mid Y}$ lets the profit-rate perturbation depend on which realization of that error occurred. The object is the same double average — only now uncertainty is propagated from two sources instead of one.

    This last equation is not a mathematical flourish; it is the reason the empirical section spends so much effort on multiple imputation. National accounts don’t hand anyone a clean measurement of capital advanced by sector — it has to be reconstructed from incomplete data, and that reconstruction carries its own error. Equation (11) is the license to treat that error as a random variable to be averaged over rather than a nuisance to be ignored. The uncertainty is propagated externally — by a generator outside the statistical model itself — rather than estimated as an internal parameter of the dynamic model: estimating $K$’s error inside the model would confound it with the model’s own measurement-noise term, opening a ridge of non-identification between two magnitudes that the data alone cannot tell apart. Kept external, twenty-five complete reconstructions of the data are generated first, each respecting the Marxian aggregate identities to machine precision, the dynamic model is fit on each, and the twenty-five fits are combined by Rubin’s rule. That is the outer average of equation (11), computed by literally drawing from the distribution of $Y$ instead of assuming it away.

    The Engine: A Three-Level Ornstein–Uhlenbeck Cascade

    Equations (9)–(11) define the target; they don’t generate a path toward it. The explanans — the mechanism that actually produces a year-by-year trajectory consistent with that target — is a hierarchical Ornstein-Uhlenbeck process with up to three nested levels, fit as a single Stan program (the same program handles one, two, or three levels, which guarantees that adding levels can never silently break the simpler cases nested inside them). All series enter standardized; time is discretized one year at a time using the Euler–Maruyama scheme.

    Level 1 — The Market Price
    $$ dev_{t,s} = \varphi_{t-1,s} – \Phi_{t-1,s} $$
    $$ \kappa^m_{t,s} = \kappa_{\mathrm{cap}} \cdot \mathrm{invlogit}\!\left(\kappa_s + \beta_1\, z^{TMG}_t\right) $$
    $$ \Delta\varphi_{t,s} = \kappa^m_{t,s}\!\left(-\,dev_{t,s}\right) \;+\; a_{3,s}\, dev_{t,s}^{\,3} \;+\; \gamma\, COM^{std}_{t,s} \;+\; \varepsilon_{t,s} $$

    Subscripts $s$ (sector) and $t$ (year) run throughout. $dev$ is last year’s gap between market price and the latent production price. $\kappa^m$ is the sector’s reversion speed, passed through a logit link that caps it inside $(0, \kappa_{\mathrm{cap}})$ and lets the general rate of profit ($z^{TMG}$) modulate it without ever pushing the system out of the stable region of the discretization. $\varepsilon$ is a fat-tailed (Student-t), stochastic-volatility innovation, so volatility can cluster in time without destabilizing the mean.

    Read the Level 1 line as a spring. The term $-\kappa \cdot dev$ is the restoring force: it pulls the market price back toward the production price with a force proportional to how far it has drifted. The cubic term $a_{3,s} \cdot dev^3$, with $a_{3,s}$ constrained negative by construction — not estimated, imposed — makes that restoring force grow faster than proportionally once the deviation gets large: the further the market strays, the harder it snaps back. This is a declared stability assumption, not a discovery: it guarantees the model can never generate an explosive regime, at the real cost that if such a regime existed in some sector of the actual economy, this particular specification could not detect it.

    Levels 2–3 — Where the Latent Center Itself Reverts
    $$ \mu_{s,t} = m_{0,s} + m_1\, G’_t + m_v\, V_{s,t} $$

    The production price $\Phi$ is not treated as a fixed, observed index; it is itself a latent state that reverts — more slowly, with its own sector speed $\kappa_p$ — toward this mean $\mu$. $m_1$ is the channel running through the general rate of profit; $m_v$ is the coefficient measuring how strongly the production price tracks the directly-constructed value $V_{s,t} = k + p$ (Level 3, and the reason the cascade goes up to three levels rather than stopping at two).

    This is the bridge back to the abstract equations above, term by term. $\mu_{s,t}$ is the estimable stand-in for the right-hand side of (9): $m_{0,s} + m_1 G’_t$ plays the role of $k + K \cdot E[G’]$, and $m_v V_{s,t}$ is the specific functional form chosen for the value-tracking channel that the abstract definition deliberately leaves open (the paper is careful to say that capitalist competition as a function of the value structure is declared at the level of equations 9–11, not derived; giving it the concrete shape $m_v V$ is a modeling choice made at the cascade level, defended by how it performs under validation rather than deduced from the definition). And the expectation of $G’$ from equation (9) has its operational counterpart in the profit rate averaged across the twenty-five multiple imputations — the mechanism equation (11) licenses.

    The coefficient $m_v$ carries real theoretical weight: it is the empirical stand-in for Chapter 9’s claim that prices of production gravitate around values. It is given a neutral prior, $m_v \sim \mathcal{N}(0,\, 0.5)$ — centered at zero, symmetric, assigning equal plausibility to $m_v > 0$ and $m_v < 0$ before seeing any data. That matters for the same reason a fair coin matters in a coin-flip experiment: if the data carried no signal, the posterior would sit wherever the prior put it, hugging zero. It doesn’t. It lands at $m_v \approx 1.0136$ with $P(m_v > 0) = 1$ — evidence that the data moved it there, not the prior. The anchoring to value is found, not assumed into the setup.

    In Plain Language

    The cascade is three springs stacked on top of each other. The market price is tied by a spring to the latent, unobserved production price. The production price is tied by its own, slower spring to a moving target that blends the general rate of profit with the directly-measured labor value. Pull any one spring and let go: it doesn’t snap to a fixed point, it settles into the kind of perpetual, decaying oscillation that equations (9)–(11) describe as an average. The springs are estimated from sixty-one years of real U.S. data, not assumed; the coefficient tying prices of production to values, specifically, could have come back negative or zero — the model gave it every chance to — and it didn’t.

    What the Numbers Say

    The empirical core of the paper is a panel of 37 productive branches of the United States economy over 61 years, from 1960 to 2020. The hypothesis tested encloses three distinct relationships, and the paper is meticulous about not conflating them. Each is stated, tested, and reported separately.

    Market Prices ↔ Prices of Production: The Strongest Link

    This is the relationship with the firmest statistical support, confirmed through six independent lines of evidence:

    Central Finding

    Gravitation exists, and it is slow. The median speed across sectors is $\kappa_m = 0.0770$, equivalent to a half-life of approximately 9 years. Market prices take about a decade to cover half the distance toward their production-price center. This is consistent with Marx’s characterization of gravitation as a tendential, mediated regulation, not an instantaneous fit.

    The number is remarkably stable under stress tests:

    • Removing five of the six productive blocks from the panel barely moves the estimate — it shifts in the third decimal place. The sixth, which gathers 18 of the 37 sectors, does produce a shift (from 9 years to 6 years), and the paper decomposes it: about half the acceleration is the generic effect of halving the panel — removing 18 sectors at random already gives 0.0929 — and not the block itself.
    • Dismantling the value anchor in three different ways — including permuting surplus value across spheres — moves the speed in the third decimal place. This is significant: it means the conclusion about market-to-production gravitation does not depend on the less robust production-to-value link.
    • The market deviation has its own dynamic signature. Compared against a random walk matched in variance, three out of six test statistics separate cleanly (the weighted-sum convergence reaches a tolerance of 0.01 while the null never reaches a tolerance ten times more lenient; recurrence analysis laminarity triples the null; recurrence entropy doubles it). The ones that don’t separate are recurrence-analysis determinism and the two deterministic-chaos invariants — the Lyapunov exponent and the correlation dimension — which the paper never claimed to find.
    • The estimate is invariant to secondary methodological choices. Sweeping the latency regularizer across three values produces life medias of 9 years in all three arms (speeds of 0.0774, 0.0770, 0.0772).
    • The known bias of disaggregation pushes against the result. Splitting a national figure among 37 branches is underdetermined and biases speed estimates downward — meaning the true half-life is probably 7–8 years rather than 9. A bias that works against your conclusion is one you can live with, because the result holds despite it, not thanks to it.

    Prices of Production ↔ Values: The Thinnest Leg

    This is the weakest part of the empirical argument, and the paper states so with complete transparency. The problem is not a defect of the instrument but a property of the object:

    Methodological Transparency

    The coupling coefficient estimated within the dynamic model is $m_v = 1.0136$ with a 95% credible interval of $[1.0096,\; 1.0176]$ — but the same procedure returns 1.0365 when surplus value is permuted across spheres, preserving all annual aggregates. Why? Because production price and value share the cost price, which explains 66.1% of the variance of the former and 72.0% of the latter, and their correlation in levels is 0.9987. The coefficient would land near one even if the law of value didn’t hold at all. The paper therefore reports it as a consistency check, not as evidence.

    The real support for this relationship comes from cross-sectional tests, not from the dynamic coupling. When temporal common trends are removed and analysis is conducted within-year, the slope of the markup on own surplus value is 0.675 with the true data versus 0.090 under permutation, with intervals that don’t come close to overlapping. The sectoral ordering of the wedge between $\Phi$ and $V$ has an inter-annual rank correlation of 0.986 and a 60-year value of 0.558 — highly persistent structure, not noise.

    A collateral finding worth noting: the coefficient of variation of sectoral profit rates is 0.669 — meaning profit rates across industries show considerable and persistent dispersion. Far from contradicting the theory, this dispersion is the condition of existence of the mechanism: if profit rates were already equalized, there would be no differential to drive capital migration, and gravitation would have nothing to operate on. Marx postulates equalization as a tendency, not an accomplished fact.

    Market Prices ↔ Values: Sustained in Form, Adjusted in Existence

    The structural modification across sectors exists and is nonlinear (the nonlinearity step holds comfortably at 6.8 null deviations). But the existence step is adjusted: 44% of its gain is obtained equally with sectoral characteristics unpaired from their spheres, and the gap against the maximum null is on the order of one paired standard error. The coefficients survive a deliberately severe correction for serial dependence (tripling the error).

    The Instrument Behind That Number: A Nested Ladder in gdpar

    That test is a small ladder of nested distributional-regression models, fit with gdpar (Gómez Julián, 2026b), the author’s own R package for generalized distributional parameter regression, published on CRAN on July 15, 2026. The ladder climbs from a bare model — “the market-to-value ratio has no sector-specific correction at all” — through a model where organic composition, wage share, and sector size shift that ratio linearly, up to a model where the correction is a flexible spline rather than a straight line. Two gains matter, measured in units of predictive density: adding the linear correction buys 207.3 units; letting it curve buys another 215.1. Both were checked against a control built to be hard to pass — shuffling which sector gets which characteristics 99 times, refitting each time, with the spline’s knots held fixed across every shuffle so the comparison can’t be won by a better basis alone. The curvature gain clears its null with room to spare (6.8 null standard deviations; the best of 99 shuffles reaches only 114.8 against 215.1 observed). The existence gain is honestly reported as thinner: shuffled sectors still buy about 44% of the real gain merely by having some characteristics to fit — three covariates and an intercept give a model room to accommodate noise even when it is being told nothing true — so the genuine margin over the null sits at about one paired standard error (23.2, against a gap of roughly 24 units). Both numbers are reported together, precisely so the large one isn’t read alone.

    A companion specification, estimated in the same gdpar fit, asks the same question about dispersion rather than location: not where the market-to-value ratio is centered, but how tightly it clusters. Larger sectors and sectors with higher capital composition show systematically less relative dispersion — elasticities of $-0.226$ and $-0.104$ — consistent with equalization operating more effectively where capital is more concentrated. Both effects clear a “breaking factor” (the multiple of the standard error at which the 95% interval would first touch zero) north of six and four respectively, past the 2.94 ceiling reached anywhere else among this paper’s location coefficients, and the finding reproduces under a completely different likelihood family (a gamma distribution on the price ratio) to within 5.2%.

    Three Failures That Confirm the Theory

    One of the most intellectually striking features of this paper is how it handles results that, at first glance, look bad for its thesis. There are three, and the paper reports all of them without softening — then shows deductively why each one was expected if the theory is correct.

    Negative Result No. 1

    The model does not out-of-sample predict better than a random walk. But this was deductively implied by the slow form of the thesis. At a horizon much shorter than the half-life, a mean-reverting process is, to first order, a random walk. If something takes a decade to get halfway back, looking at a single year won’t let you see it return.

    Negative Result No. 2

    The value term is predictively indistinguishable. Again, this follows from the slow coupling between prices of production and values: with half-lives on the order of decades and only 61 years of data, univariate root-unit tests are structurally underpowered.

    Negative Result No. 3

    No univariate test separates the true wedge from its permuted placebos. But this was predicted before measuring, by the persistence of sectoral ordering itself (inter-annual rank correlation of 0.986). A highly persistent time series is hard to distinguish from its permuted version using tests designed for shorter memory.

    Finding these signatures is corroboration of the slow form of the thesis, and not finding them would have been the real problem. — Gómez Julián, on the negative results

    The paper’s stance on this is worth highlighting: “Lejos de refutar la tesis, los tres están deductivamente implicados por su forma lenta” — far from refuting the thesis, all three are deductively implied by its slow form. A single mechanism (slow gravitation) explains both the substantive thesis and all the apparently negative results, and it also survives in the validated posterior. “That a single cause explains the thesis and all the apparently negative results, and that it additionally survives in the validated register, is the opposite of a petitio principii: it is a unified, falsifiable, and internally validated narrative.”

    Temporalism Isn’t a Preference — It’s a Condition of Measurement

    Perhaps the most consequential result in the entire paper is not a number but a statement about what can and cannot be measured. It concerns the “modulator” — the component of Marx’s argument in which the general rate of profit enters into the structural modification of each sphere, meaning the deviation of each sphere is not independent of the reference but generated by it.

    The Identifiability Argument

    When the model was run with a single, fixed general rate of profit for all 61 years (as a simultaneous approach would require), the posterior exhibited a flat ridge: two completely different functional bases (a degree-two polynomial and a spline basis) produced the same pathology to the third decimal place, with an effective sample size of only six draws. The diagnostic got worse with more sampling (R-hat rising from 1.33 to 1.73). This is the unmistakable signature of a direction in parameter space along which the likelihood does not change.

    The cause is theoretical, not computational. With one fixed reference, the modulator can only be identified evaluated at that single point — a single number, not a function over the space of references. You cannot estimate three coefficients from a polynomial if you have one data point.

    When the reference was allowed to vary year by year (61 different general rates of profit), the model converged within minutes, with a large improvement in both time and effective sample size, and zero divergences.

    Named, Not Improvised: Theorems 1A and 1E

    This diagnosis isn’t an ad hoc read of a misbehaving sampler. gdpar (Gómez Julián, 2026b) — the same package behind the nested ladder above — ships a formal identifiability result for exactly this situation. Its Theorem 1A establishes that, with a single fixed reference point, a distributional modulator is identified only at that point: as one number, not as a function over the space of possible references. Theorem 1E is the positive counterpart: letting the reference vary restores identifiability of the modulator as a function. Fitting a degree-two polynomial (three coefficients) or a five-knot spline basis (five coefficients) against one single, unmoving reference asks for more than a single data point in that dimension can support — which is exactly what a flat likelihood ridge looks like from the sampler’s side.

    The figures behind the improvement, precisely: a fixed reference with a degree-two polynomial gives an R-hat of 1.7333, an effective sample size of 6, and 8 divergent transitions in 39 minutes; a one-knot spline basis reproduces the same pathology — R-hat 1.7335, effective sample size 6, 14 divergences, 5.6 hours. Letting the reference vary year by year (61 distinct annual values of the general rate of profit), centering the additive component and raising the sampler’s adaptation parameter to 0.99, gives an R-hat of 1.0035, an effective sample size of 1332, and zero divergent transitions — in 2.9 minutes. That is the 115-fold improvement in time and 222-fold improvement in effective sample size referenced above, and it is a theorem, not a tuning trick: no amount of additional sampling closes that gap under a fixed reference, because the object being asked for — the modulator as a function — simply is not there to find.

    The consequence is stated precisely: with a single fixed general rate of profit obtained by solving the system simultaneously, the claim of Chapter 9 of Volume Three of Capital is unverifiable by construction. It is not that the data are insufficient — the object is not identified, and no amount of data would identify it. The argument does not establish that simultaneism is false as a description of capitalism (that is established by historiography and sociology); it establishes that a simultaneous procedure cannot, even in principle, empirically verify the specific part of Marx’s argument that this work estimates.

    In Plain Language

    Marx says: first a general rate of profit forms, then each industry deviates from it according to how capital-intensive it is. To check whether the deviation depends on the general rate, you need to see what happens to the deviation when the general rate changes. If you calculate one general rate for the entire 61-year span, it never changes, and there is nothing to observe. That is exactly what happened: the model with one fixed rate doesn’t converge — not because of computational limitations, but because it is being asked to measure a relationship with a single observation of one of the two variables. Calculating one rate per year — which is what the temporal reading says you should do — the same model converges in three minutes.

    What This Is, and What It Isn’t

    The paper is careful, almost painstakingly so, about the limits of what it claims. This section matters because a reader coming from the “pro-Marx” or “anti-Marx” side might be tempted to over-read the results. The author doesn’t let you.

    What the evidence authorizes: In the United States between 1960 and 2020, market prices gravitate toward prices of production with a decadal half-life that is sectorially heterogeneous, and this speed survives three independent assaults (removing five of the six productive blocks, destroying the value anchor, varying secondary methodological decisions). This is a measured, calibrated, and falsifiable fact.

    What the evidence does not authorize:

    • It does not claim superior predictive power (the model does not out-predict a random walk, which was expected).
    • It does not claim that univariate root-unit tests confirm gravitation (they are structurally underpowered at this time scale).
    • It does not claim uniqueness or categorical novelty. The contribution is the explicit integration and canonization of a slow gravitation cascade with value anchoring, measured on real data, with propagated uncertainty, validated, and subjected to a diagnostic whose unfavorable results are reported alongside the favorable ones.
    • It does not claim that this statistically demonstrates the law of value, “and not for rhetorical prudence but because it would be false: a price series can show that a magnitude behaves as the law predicts, and cannot explain why that magnitude exists or whether the category with which we name it is the correct one.”

    That last point is the paper’s deepest epistemological commitment. Questions about whether “value” is the right category for what prices ultimately measure are not answerable by any price series, no matter how long. They are answered by history, sociology, and philosophy — and the firm answer is the one obtained when all four disciplines (those three plus statistics) point in the same direction. The four-dimensional convergence is the argument, not any single leg of it.

    The paper also addresses the homology that unifies its seemingly disparate halves — the historiographical-filosofical first chapter and the econometric second chapter. The relationship between necessity and contingency that governs the transition from feudalism to capitalism (where the same demographic shock produced opposite outcomes in different regions of Europe) is structurally identical to the relationship between prices of production and market prices. A law determines the center; circumstances determine each particular outcome. Neither fact negates the other, because they describe different levels of the same reality.

    What It All Adds Up To

    Here is the simplest version of what this 260-page paper establishes:

    Marx was reproached for a century for having done an arithmetic calculation wrong. What happened is that his calculation was redone under an assumption he never made: that the prices of things bought to produce and the prices of things that come out of production are the same prices, fixed at the same time. If you assume that, Marx’s accounts indeed don’t close. But that assumption is equivalent to saying the economy doesn’t happen in time. As soon as you accept that what exits the factory this year is what enters the factory next year, the accounts close without anyone having to fix anything. — Gómez Julián, Summary for the Reader

    But recognizing the conceptual error was only the first half. What had been missing — and what this paper contributes — is doing those accounts with real data instead of with fictitious numerical examples, which is what the school that had the correct conceptual reading had never done.

    The empirical results show that prices in the U.S. economy over six decades do behave as the theory predicts: they gravitate, slowly, toward prices of production calculated with Marx’s theory and no other. This finding survived every attack the author could devise — removing productive sectors, destroying the value anchor, permuting surplus values, varying methodological decisions, and running diagnostics whose unfavorable results are reported in full alongside the favorable ones.

    The part of the argument linking prices of production to labor values is also supported by real evidence, though less firmly, and the paper says exactly where the weak points are and why they are properties of the object, not defects of the instrument.

    And the paper does not claim to have demonstrated the law of value with a series of numbers, because “questions of that kind are not answered with numbers: they are answered with history, with sociology, and with philosophy, and the firm answer is the one obtained when the four things (the previous three, together with statistics) all point in the same place.”

    That convergence doesn’t make the result eternal — better evidence can overturn it tomorrow. But it makes it, for now, “our best possible approximation to the truth.”

    — — —

    “In science as in life, overcoming adversity is what makes us truly strong.”

    This post summarizes the introduction, conclusions, and the formal-empirical chapter (§2.4) of Gómez Julián, J. M. (2026). Some Reflections on Marx’s Prices of Production: Historicity of the Law of Value, Dialectical-Materialist Foundation, and Dynamic Formalization Under Uncertainty. Zenodo. https://doi.org/10.5281/zenodo.21842251. The full paper spans approximately 260 pages across two chapters covering philosophy, historiography, mathematical formalization, and empirical econometrics. Equations (9)–(11) and the model specification cited here reproduce that chapter’s notation; gdpar is cited separately as Gómez Julián (2026b).

    Written for the curious. An invitation to read.

  • Is It Scientifically Possible for Central America To Be a Single Country?

    Is It Scientifically Possible for Central America To Be a Single Country?

    Political Science & History

    Science, Youth, and the Rebirth of a Central American Nation

    The Origins of Scientific Unionism in Central America and Its Unavoidable Future

    History is rarely kind to fragmented nations. At the dawn of the 20th century, Central America was a collection of small, vulnerable republics plagued by authoritarian rule, economic volatility, and the looming shadow of international imperialism. Yet, from the cloistered halls of the University of San Carlos in Guatemala, a quiet revolution was brewing. It was led not by generals, but by students. This is the story of how a group of young intellectuals pioneered “Scientific Unionism”—a movement to reunite Central America not through romantic nostalgia, but through the rigorous application of social sciences.

    Based on Margarita Silva Hernández’s illuminating research, this post explores the historical genesis of this movement. Furthermore, it asks a vital question for today’s political scientists and economists: If Scientific Unionism was valid a century ago, is it not an absolute, long-term historical inevitability for Central America’s survival on the global stage today?

    The Catalyst: 1898 and the Shift in Global Power

    To understand the birth of Scientific Unionism, we must look at the pivotal year of 1898. The Spanish-American War resulted in a resounding victory for the United States, establishing it as a first-rank global power with expansionist ambitions in the Caribbean and Central America. For a group of young university students, this was not merely a geopolitical shift; it was an existential threat. They perceived the conflict as a clash between the Anglo-Saxon and Latin worlds, sparking a profound anti-imperialist consciousness.

    Simultaneously, the region was suffering the aftershocks of the 1897 coffee price crash. The liberal economic model, heavily reliant on agricultural exports and foreign capital (like the newly formed United Fruit Company), had left the isthmus vulnerable. The students saw the economic crisis as a symptom of a deeper disease: the fragmentation of Central America. To them, the petty dictators of the region were complicit in this backwardness, suppressing social mobility and selling out national resources.

    The Birth of Scientific Unionism

    On June 18, 1899, a clandestine group of students formed a society called El Derecho (The Law). Led by a young Nicaraguan, Salvador Mendieta, these students—mostly in their late teens and early twenties—originated from across the isthmus. They were the children of provincial merchants and professionals, united by a shared frustration with the lack of political mobility under authoritarian regimes.

    What set El Derecho apart from previous attempts at Central American unity was their methodological approach. They did not want to simply restore the old Federal Republic of the 1820s through military decrees. Instead, they turned to sociology. Influenced by the positivist ideas of Auguste Comte, Herbert Spencer, and John Stuart Mill, they sought to discover the “social laws” governing Central America.

    “They designated their movement ‘scientific unionism’ to evidence the intellectual condition of its founders and the scientific-social bases of their working methods.”

    Their thesis was clear: Central America was a single nation artificially divided. To reunite it, one could not rely on mere political pacts (which had repeatedly failed, such as the brief “Greater Republic” in 1898). Instead, they needed to build a cultural unity. They believed that through civic education, the eradication of localism, and the application of scientific principles to governance, they could forge a strong, unified state capable of resisting foreign intervention and achieving modernization.

    From Theory to Political Action

    The students of El Derecho did not remain in the classroom. They organized five Central American Student Congresses between 1901 and 1911, creating a regional network of young thinkers. They published pamphlets, established night schools for workers, and delivered public conferences. They positioned themselves as the intellectual vanguard destined to replace the old oligarchic guard.

    Naturally, this provoked the wrath of local dictators. Manuel Estrada Cabrera in Guatemala met their denunciations with brutal repression. Students were imprisoned—some, like Marciano Castillo, dying in the penitentiary—and the movement was forced into exile. By 1904, the students had evolved into a formal political entity: the Central American Unionist Party (PUCA). The student movement had matured into a regional political force.

    A Modern Perspective: The Inevitability of Union

    The preceding sections summarize the historical findings of Margarita Silva Hernández. The following section represents the extrapolation of this blog’s author, using the historical foundation of Scientific Unionism to pose contemporary political and economic questions.

    When Salvador Mendieta and his peers looked at Central America in 1899, they applied the scientific method to diagnose a fractured region. If we apply modern political science and economic theory to Central America today, does the scientific case for union remain valid? The data suggests not only that it is valid, but that it has become a historical inevitability.

    Geopolitical Scale and Relevance: In the 19th century, Mendieta feared absorption by the US. Today, the threat is irrelevance in a multipolar world dominated by giants. A united Central America would encompass a territory of approximately 423,000 square kilometers—larger than Germany. This is not merely a trivia fact; it implies a geopolitical footprint capable of negotiating on equal terms with global powers, managing its own maritime routes, and securing a strategic position between two oceans.

    Diversifying the Production Matrix: Historically, the region has suffered from a monoculture export model (coffee then, and various agricultural or low-tier assembly maquilas now). A unified state would possess an unprecedented diversity of microclimates, resources, and cultural demographics. This diversity would allow for a scientifically planned diversification of the production matrix. The agricultural backbone (coffee, bananas, sugarcane, livestock) would not be abandoned, but rather complemented. A single Central American market of over 50 million people provides the necessary domestic consumer base to justify intense, state-sponsored industrialization. It creates a rationale for heavy infrastructure, regional supply chains, and a unified digital economy.

    The Science of Scale: Modern economics validates the original premise of Scientific Unionism. Fragmented states suffer from duplicated bureaucratic costs, border frictions, and an inability to capture economies of scale. A unified Central America would eliminate these inefficiencies. It could pool its scientific and intellectual capital—much like the students of El Derecho envisioned—into a single educational and technological ecosystem.

    Therefore, the question is no longer merely historical. If Central America wishes to be more than a peripheral zone of extraction for larger economies, union is not a romantic dream of the past; it is a scientific, economic, and historical necessity for the future. The students of 1899 understood the math of their era. We must be brave enough to do the math of ours.

    ~ Exploring the past to architect the future ~

  • Fiscal and Monetary Policy Usually Hold Hands

    Fiscal and Monetary Policy Usually Hold Hands

    Fiscal and Monetary Policy Usually Hold Hands: What 60 Years of U.S. Data Reveal About Economic Independence

    Fiscal and Monetary Policy Usually Hold Hands

    What 60 years of U.S. data reveal about the myth of independent economic instruments

    Imagine you are steering a ship with two sets of controls—one for the rudder and one for the engine. Conventional wisdom says these controls work independently: you can adjust the rudder without affecting the engine, and vice versa. For more than seventy years, this is essentially how mainstream economics has treated a country’s fiscal policy (government spending and lending) and its monetary policy (interest rates and central bank operations). Each set of tools was supposed to be independent of the other, allowing policymakers to pursue multiple goals at the same time without interference.

    A new study published in the Revista Cubana de Economía Internacional challenges that assumption head-on. Using six decades of quarterly U.S. data—from January 1960 to October 2022—and a battery of modern Bayesian statistical techniques, economist José Mauricio Gómez Julián finds that American fiscal and monetary instruments are far from independent. They are, in fact, deeply intertwined, both in straightforward linear ways and in more complex, nonlinear patterns. The implications ripple outward from econometric theory into the practical world of how governments manage economies.

    The Rule That Started It All

    The story begins in 1952, when the Dutch economist Jan Tinbergen—who would later share the first Nobel Memorial Prize in Economic Sciences—formulated a deceptively simple principle: to achieve n independent policy goals, you need at least n independent policy instruments. Known today as the “Tinbergen Rule,” this idea became a cornerstone of economic policy theory. It told governments that if they wanted to control inflation, unemployment, and growth simultaneously, they needed at least three tools that did not overlap in their effects.

    The American economist James Tobin later sharpened this: instruments are independent when “the effects of any instrument on the targets are not proportional to those of any other, or of any combination of others.” In modern econometrics, this independence assumption has been formalized as super exogeneity—a technical condition saying that the statistical relationships between economic variables remain stable even when policymakers intervene. If super exogeneity holds, a central bank can freely adjust interest rates without worrying that the Treasury’s spending decisions will systematically interfere with those adjustments.

    “If a central bank is free to choose the adjustments to its instruments to pursue its final objectives, it has instrument independence.”

    — Laurence H. Meyer, former Federal Reserve Governor

    The problem? Despite its foundational role in economic theory, nobody had rigorously tested this assumption econometrically for the U.S. case—until now.

    Six Instruments, Six Decades

    The study examines six economic policy instruments, divided into two groups:

    Instruments Studied

    • Fiscal instruments: Federal government current spending (GCGF) and federal government policy lending (GACL)
    • Monetary instruments: The effective federal funds rate (FEFR), the Federal Reserve discount rate (TD), other assets held by the monetary authority (TDFG), and the 3-month Treasury bill secondary market rate (LT3M)

    Data sourced from the Federal Reserve Economic Data (FRED) database and YCharts, spanning 252 quarterly observations.

    With these variables in hand, the researcher embarked on a two-stage investigation. First, he tested whether each pair of instruments showed any meaningful statistical association. Then, he built a predictive model to see whether one instrument could be reliably forecasted from the others—which would be impossible if they were truly independent.

    Stage One: Mapping the Web of Connections

    The preliminary analysis used three different correlation measures—Pearson, Kendall, and Spearman—in both their classical (frequentist) and Bayesian versions. The results were striking. Eight pairs of instruments showed significant correlations, with partial correlation coefficients at or above 0.5 in absolute value. For context, a Pearson correlation of 0.5 means one variable explains about 25% of the variation in another—a substantial relationship by any standard.

    Some highlights from the correlation analysis:

    1. The 3-month Treasury bill rate and federal policy lending showed a strong positive correlation (Pearson partial correlation of approximately 0.78).
    2. Federal policy lending and the discount rate were also strongly positively correlated (about 0.77).
    3. Federal government spending and federal policy lending were negatively correlated (about −0.69), suggesting that as one rises, the other tends to fall.
    4. Government spending showed negative correlations with all three monetary interest rate instruments (around −0.59 to −0.61).

    The fact that these correlations held across different statistical measures and survived the stationarity adjustments (seasonal corrections applied via the X-13ARIMA-SEATS method) gives them added credibility. The seasonality adjustments also provided strong evidence that the variables follow approximately normal distributions, further validating the correlation analysis.

    Linearity, Quadratics, and Beyond

    Correlation tells you that two variables move together, but not how they move together. Is the relationship a straight line? A curve? Something more exotic? To answer this, the study employed Bayesian linear regression models and RESET tests (a standard diagnostic for detecting nonlinear relationships), both reinforced with Bayesian bootstrapping—a resampling technique that generates thousands of synthetic datasets to test the robustness of results.

    The findings revealed that most instrument pairs have linear relationships, but in two notable cases—the discount rate versus policy lending, and the federal funds rate versus government spending—quadratic (curved) relationships also play a role. This means the effect of one instrument on another is not constant; it changes depending on the level of the variable, adding a layer of complexity that the Tinbergen framework simply does not account for.

    For example, the relationship between the federal funds rate and government spending follows a parabolic pattern: at lower spending levels, the federal funds rate behaves one way, and at higher spending levels, it behaves differently. This kind of interaction is precisely what “independence” was supposed to rule out.

    Stage Two: Building the Model

    Armed with a clear map of which instruments are connected and how, the researcher constructed a Bayesian Generalized Linear Model (BGLM) to predict federal government policy lending (GACL) from the other instruments. This was not an arbitrary choice: among all the instruments studied, GACL emerged as the most consistently dominated—meaning it is explained by other instruments 75% of the time rather than explaining them. It was the natural candidate for the response variable.

    To handle the nonlinear relationships identified in Stage One, the model used natural cubic splines—flexible mathematical curves that can bend to fit complex patterns without requiring the researcher to guess the exact shape in advance. Think of splines as a series of smoothly connected curve segments that together approximate any function, much like a skilled draftsman’s French curve. The model also incorporated the central bank’s asset holdings (TDFG) as a log-normally distributed random variable, based on the best-fitting distribution identified through empirical testing.

    Model Performance at a Glance

    • Average R-squared: 0.908—the model explains about 91% of the variation in federal policy lending
    • Mean Absolute Error: 68.5 (on a variable that ranges from 146 to 1,682)
    • Root Mean Squared Error: 92.8
    • Convergence (R-hat): 1.0—indicating the Markov Chain Monte Carlo simulations ran cleanly
    • Multicollinearity check: Generalized VIF values below 10 for all effective predictors

    In plain terms: a fiscal instrument can be predicted with high accuracy from a combination of fiscal and monetary instruments. If these tools were truly independent, this would be impossible. The model’s strong performance is the mathematical proof that the independence assumption does not hold.

    What Does History Say?

    The econometric findings do not exist in a vacuum. The study enriches its statistical conclusions with historical evidence from American economic policy, and the alignment is remarkable.

    Consider the Troubled Asset Relief Program (TARP), launched during the 2008 financial crisis. As former Federal Reserve Vice Chairman Alan Blinder has written, TARP “was not about cutting taxes, spending money, or lowering interest rates.” It was not purely fiscal policy, nor was it purely monetary policy. It was a hybrid—designed jointly by the Treasury and the Federal Reserve, using taxpayer money to purchase potentially depreciating financial assets. It was, in Blinder’s words, “financial stability policy, something the U.S. government had not needed since the Great Depression.”

    “TARP was not about cutting taxes, spending money, or lowering interest rates. Instead, it was about putting taxpayer money at risk by purchasing assets that could decline in value. The program was also jointly designed by the Treasury and the Federal Reserve.”

    — Alan S. Blinder, A Monetary and Fiscal History of the United States, 1961–2021 (2022)

    The same pattern recurred with the bank stress tests announced in February 2009—again a joint product of the Treasury and the Fed, again neither purely fiscal nor purely monetary. And it happened once more in 2020, when the COVID-19 pandemic demanded unprecedented coordination between fiscal stimulus checks and the Fed’s asset purchases. Each crisis forced policymakers to blur the lines between fiscal and monetary tools, confirming at the practical level what the data confirm statistically.

    So Which Side Dominates?

    One of the study’s more intriguing findings is a pattern of fiscal dominance. In five out of eight significant instrument pairings, the fiscal instrument is the “dominant” variable—meaning it serves as the predictor rather than the predicted. Federal government spending (GCGF) in particular emerges as a highly dominant instrument, while federal policy lending (GACL) is predominantly the variable being explained.

    However, this is not a clean sweep for fiscal policy. In two cases, monetary instruments dominate fiscal ones, and in one case the direction depends on whether the relationship is modeled linearly or quadratically. The overall picture is one of asymmetric but bidirectional interdependence—fiscal instruments tend to drive the relationship, but monetary instruments are far from passive.

    Why This Matters Beyond the Ivory Tower

    If you are not an economist, you might wonder why the independence of policy instruments matters. The answer is practical and consequential.

    Central bank independence—the idea that monetary authorities should operate free from political pressure—is one of the most widely advocated institutional designs of the past four decades. But this advocacy typically focuses on independence from electoral cycles: the Fed should not cut interest rates simply because an election is approaching. The study’s findings do not challenge that kind of independence. What they challenge is a different, more technical assumption: that the tools themselves operate in separate silos.

    The study concludes that fiscal and monetary authorities in the U.S. are not independent in their instruments—the Treasury’s spending decisions and the Fed’s rate decisions are statistically entangled. This does not mean that central bank independence from political cycles is undesirable or unviable. Quite the opposite: the author suggests that if fiscal and monetary instruments are this deeply intertwined, both fiscal and monetary authorities should perhaps enjoy independence from electoral pressures, not just the central bank.

    Moreover, the finding that fiscal instruments tend to dominate has a subtle but important implication: in complex economic scenarios—financial crises, pandemics, supply shocks—monetary policy alone may be insufficient. The historical record confirms this. The U.S. recovery from the 2008 crisis, which “eventually broke all longevity records,” was driven not by monetary easing alone but by an unprecedented combination of fiscal stimulus and monetary accommodation working in concert.

    Limitations and Open Questions

    The author is admirably transparent about what the study does and does not accomplish:

    1. The analysis is specific to the United States and to the 1960–2022 period. Whether the same patterns hold in other economies remains an open question.
    2. The study examines instrument-to-instrument relationships but does not directly model how these instruments jointly affect policy goals like growth, employment, and price stability—though the author recommends this as a natural next step.
    3. The model presented is robust but not necessarily the best possible model. The goal was to test the independence assumption, not to optimize predictive power, and for that purpose the model is more than adequate.
    4. The strong coordination between U.S. fiscal and monetary authorities may partly explain the findings, but the author argues that the underlying economic dynamics themselves also contribute—the variables are intertwined not just because policymakers coordinate, but because the real economy forces them to.

    The Bottom Line

    For over seven decades, mainstream economic theory has assumed that fiscal and monetary policy instruments are independent of each other. This assumption underpins the Tinbergen Rule, shapes how economic models are built, and influences how central banks are designed. The study by Gómez Julián applies modern Bayesian econometrics to 60 years of American data and finds, with considerable statistical rigor, that this assumption does not hold.

    The instruments of U.S. economic policy are deeply interdependent—in linear ways, in curved ways, and in historically documented, crisis-tested ways. A fiscal instrument can be predicted with over 90% accuracy from a combination of other fiscal and monetary instruments. The Tinbergen Rule’s condition of independent instruments is not just violated; it is violated comprehensively.

    This does not invalidate the Tinbergen framework entirely, but it does suggest that a new paradigm is needed—one that starts from the reality of interdependence rather than the ideal of independence. The economic instruments of the world’s largest economy do not work in isolation. Perhaps it is time our theories stopped assuming they do.

    · · ·

    Reference: Gómez Julián, J. M. (2023). “Análisis econométrico de las relaciones entre los instrumentos de política económica en Estados Unidos.” Revista Cubana de Economía Internacional, 10(2), 72–97. Available at: revistas.uh.cu

    This post is an accessible summary of the original peer-reviewed research article. All quantitative claims and methodological details are drawn directly from the published paper. The interpretations offered here aim to make the findings approachable for a broad audience without distorting the author’s conclusions. Readers seeking the full technical treatment are encouraged to consult the original article.

  • ON THE IMMANENT DIALECTIC IN THE COMMODITY METAMORPHOSIS

    ON THE IMMANENT DIALECTIC IN THE COMMODITY METAMORPHOSIS

    The Hidden Logic Inside Every Price Tag — Reading Marx Through Hegel’s Syllogisms
    Political Economy × Philosophy

    The Hidden Logic Inside Every Price Tag

    How Hegel’s syllogisms reveal the contradictions Marx saw in every commodity — and why those contradictions still matter for understanding capitalism’s future.

    Every time you buy a cup of coffee, two completely different things happen at once. The coffee satisfies a need — warmth, caffeine, pleasure. But it also embodies a social relationship: someone grew the beans, someone roasted them, someone set a price. That double life of every commodity is what Marx called the contradiction between use value and exchange value. An economist recently set out to show that this contradiction follows an exact logical structure — one that Marx sketched but never fully completed.

    Why This Paper Exists

    Karl Marx built his critique of political economy on the logical scaffolding of the German philosopher G.W.F. Hegel. This is not a minor footnote: Hegel’s dialectical logic — the idea that concepts develop through contradiction, moving from thesis to antithesis to synthesis — is the engine room of Capital. Marx famously said he turned Hegel “right side up,” replacing idealism with materialism. But he kept the machinery.

    The problem, as Gómez Julián points out, is that Marx never finished the philosophical job. He used Hegel’s logic to analyze commodities, money, and prices, but he never fully explained how the internal contradictions of the commodity resolve themselves at the level of pure logic. He identified the cycle M–D–M (commodity–money–commodity) and even mapped it onto Hegel’s qualitative syllogism. But then he stopped the philosophical analysis and moved on to economics. This paper tries to pick up where Marx left off.

    “The contradiction between use value and exchange value is one of the most fundamental discoveries of Marxian Economics, a principle without which all the conclusions of the theory of value and money remain dead.”
    — Roman Rosdolsky, cited in the article

    Three Words You Need: Use Value, Exchange Value, Money

    Before going further, let’s make sure the key terms are crystal clear — no economics degree required.

    • Use value is what a thing is good for. A coat keeps you warm. Bread feeds you. This is qualitative — it answers the question “what does it do?”
    • Exchange value is what a thing can be traded for. The coat might be worth three loaves of bread, or $80. This is quantitative — it answers the question “how much is it worth?”
    • Money is the universal translator. It lets every commodity express its exchange value in one common language (dollars, euros, colones). But money also separates buying from selling, creating new contradictions.

    The central tension is this: a commodity is both a useful object and a bearer of abstract social value. These two identities don’t sit comfortably together. The article’s claim is that this tension follows a precise logical structure that Hegel’s system can decode.

    Hegel’s Toolkit: Concept, Judgment, Syllogism

    Hegel’s Science of Logic develops in three stages that mirror how we think. Gómez Julián draws on all three:

    The Concept (Begriff) has three “moments”: universality (what something shares with everything in its class), particularity (what distinguishes it within that class), and singularity (the concrete, individual thing that unites both). Think of it this way: “fruit” is universal; “citrus” is particular; “this orange in my hand” is singular.

    The Judgment (Urteil) is what happens when those moments are set against each other — when we say something is this but also is not that. It’s the moment of contradiction.

    The Syllogism (Schluss) is the resolution. It’s the logical form in which the contradiction finds its movement — not by disappearing, but by developing into something richer. A syllogism has a major term (universal), a minor term (particular), and a middle term (singular) that mediates between them.

    Everyday Analogy Imagine a job market. Workers (particular individuals) want wages (universal standard). The job interview is the singular mediation — the concrete encounter where “this worker” meets “the market price for labor.” The contradiction between what a worker needs and what the market offers doesn’t vanish; it plays out in the negotiation. Hegel’s syllogism captures the logical skeleton of exactly this kind of process.

    Syllogism No. 1 — The Act of Buying and Selling

    The first syllogism Gómez Julián develops is what Hegel calls the syllogism of reflection in its exclusive form. It addresses the most basic question: how can a commodity and money — two fundamentally different things — be exchanged at all?

    Consider the act of selling (M → D). The seller has a particular commodity — say, a specific handmade chair. Money plays the role of the universal: it’s the general equivalent against which all commodities measure themselves. What bridges the two? The social nexus — the web of production relations, market norms, and shared conventions that make exchange possible in the first place.

    In the act of buying (D → M), the logic mirrors itself: money (now universal) is exchanged for a particular commodity, again mediated by the social nexus. The syllogism looks like this:

    Selling: M → D Particular (commodity) — Singular (social nexus) — Universal (money)

    Buying: D → M Universal (money) — Singular (social nexus) — Particular (commodity)

    The key insight is that the social nexus is not an add-on — it is the logical middle term. Without it, the contradiction between a chair and a stack of bills would be irreducible. Marx himself recognized this when he wrote that “a relation of social production appears as something existing outside individuals.” The chair doesn’t inherently “know” it’s worth $200. That knowledge is embedded in social practice.

    Syllogism No. 2 — Price vs. Value

    The second syllogism tackles a subtler problem. Even after an exchange happens, there’s a gap: the price of a commodity almost never equals its value (the socially necessary labor time embedded in it). Prices fluctuate with supply, demand, speculation, season, mood. Marx acknowledged this explicitly:

    “The price-form … allows for the possibility of a quantitative incongruity between price and the magnitude of value — that is, a deviation of the former from the latter.”

    Gómez Julián uses Hegel’s syllogism of analogy to model this. In this syllogism, the middle term is a singularity taken in its essential universality — a particular thing considered not just as itself but as representative of its genus. Here’s how it maps:

    Price–Value Relation: S — U — P Singular: exchange value (the real labor time, which never appears directly on the market — it enters the “capricious volatility of competition”)
    Universal: price (the monetary expression, which carries value inside it but also differs from it — “value in-itself and also value distinct from itself”)
    Particular: exchange value over the long run (the average around which supply and demand oscillate)

    The punchline is elegant: price and value are never identical at a single point in time, but value is always the gravitational center around which prices orbit. This is not a failure of the system — it’s the way the contradiction moves. As Marx wrote, echoing Hegel: identity here is “the identity of negation.”

    Think of It Like This A stock’s price on any given day can be wildly off from its “intrinsic value” (however you measure it). But over time, market forces push the price back toward something like fair value. The deviation is not noise — it’s how the market processes information. Gómez Julián is arguing that this pattern is not just an empirical regularity but a logical necessity embedded in the structure of commodities.

    Syllogism No. 3 — The Big One Marx Identified But Didn’t Complete

    Marx himself noticed that the cycle M–D–M (commodity–money–commodity) can be mapped onto Hegel’s qualitative syllogism P–U–S (particular–universal–singular). The two M’s in the cycle play different roles:

    The first M is particular — it’s a specific commodity I own and want to get rid of (say, the chair I made). The D (money) is universal — it can buy anything. The second M is singular — it’s the concrete commodity I actually need (say, groceries). The money mediates, translating my particular surplus into the particular thing I lack.

    But here’s where the article makes its most original contribution. Marx only named the syllogism and stopped. Gómez Julián argues that the full Hegelian development reveals something Marx left implicit: the commodity embodies both social labor (exchange value) and private labor (use value). Money — as the “universal equivalent” — is the form in which these two kinds of labor temporarily reconcile. But reconciliation is not resolution. The contradiction persists and drives the system forward.

    “The development of the commodity does not suppress this contradiction: rather, it creates the forms in which it can move.”
    — Marx, cited in the article

    Marx compared this to planetary motion: a body is constantly falling toward the sun and constantly being flung away. The orbit is not a resolution of gravity vs. inertia — it is the contradiction in motion. Commodity circulation works the same way.

    From Logic to Collapse: The Tendency of the Rate of Profit to Fall

    The paper doesn’t stop at philosophy. It follows the thread all the way to what Marx considered the long-run fate of capitalism: the tendency of the average rate of profit to fall.

    The logic runs as follows. The average rate of profit is the weighted average of profit rates across all sectors of the economy:

    Average Rate of Profit g'M = Σ wᵢ · g'ᵢ

    where g'M = average profit rate, wᵢ = weight of sector i‘s capital in total social capital, g'ᵢ = profit rate in sector i.

    As capitalism develops, technological innovation replaces living labor (variable capital) with machinery and materials (constant capital). This raises productivity — each worker produces more. But it also means each commodity contains less total labor time and therefore less surplus labor time (the source of profit). Even though the proportion of surplus time within each commodity may rise (higher exploitation rate), the absolute mass of surplus per unit falls.

    To compensate, capitalists must produce at exponentially larger scales — what Marx called the “faux frais” (overhead costs) of production and circulation. Meanwhile, technological unemployment grows, wages are pressured downward, and social tensions mount. The article presents this as the logical terminus of the contradictions embedded in the commodity itself.

    For Non-Economists Imagine a bakery that replaces bakers with machines. Each loaf now costs less labor to make, so the profit per loaf shrinks. The bakery compensates by selling far more loaves — and by cutting the remaining workers’ wages. Scale this across the whole economy, and you get Marx’s picture: profits per unit fall, production must explode, workers are squeezed, and the system becomes increasingly fragile. That’s the “falling rate of profit” thesis.

    Why Does This Matter?

    You don’t have to agree with Marx’s conclusions to appreciate what this paper accomplishes. It demonstrates three things:

    • Hegel’s logic is not decorative. The syllogistic structures are not metaphors — they are the formal architecture that makes Marx’s economic categories cohere. Ignoring them leaves Capital half-read.
    • Contradictions are not bugs — they’re features. The gap between use value and exchange value, between price and value, between private labor and social labor, is not a flaw in capitalism. It’s the mechanism that keeps it moving. Understanding this changes how you think about crises: they’re not accidents but structural expressions of unresolved logical tensions.
    • The long-run trajectory matters. Whether or not capitalism “collapses” in the dramatic sense Marx envisioned, the falling-rate-of-profit framework offers a structural explanation for secular stagnation, financialization, and the persistent pressure to expand into new markets — themes that remain urgently relevant.
    · · ·

    At its heart, Gómez Julián’s paper is an invitation to read Marx the way Marx read Hegel — not as a collection of slogans, but as a living logical system where every economic category carries a philosophical skeleton inside it. The commodity is not just a thing with a price. It is a logical knot tying together private desire, social labor, monetary abstraction, and historical trajectory. Untying that knot — or at least seeing its shape — is the first step toward understanding why economies work the way they do, and why they sometimes don’t.

    Original article: Gómez Julián, J. M. (2017). “Sobre la dialéctica inmanente en la metamorfosis mercantil.” Revista de Filosofía, Universidad de Costa Rica, 56(145), 45–53. ISSN 0034-8252.

    About the original author: José Mauricio Gómez Julián holds a B.A. in Economics from Universidad Latina de Costa Rica. The paper was received in April 2016 and approved in June 2016.

    This blog post is an explanatory summary, not a peer review. For the full mathematical derivations and primary-source quotations, consult the original article.

  • HOW TO CONDUCT ECONOMIC POLICY IN THE PRESENCE OF A FIXED CAPITAL SURPLUS OR DEFICIT WITHOUT RESORTING TO PAPER MONEY?

    HOW TO CONDUCT ECONOMIC POLICY IN THE PRESENCE OF A FIXED CAPITAL SURPLUS OR DEFICIT WITHOUT RESORTING TO PAPER MONEY?

    How Can Economic Policy Address Fixed-Capital Surpluses or Deficits Without Resorting to Paper Money?
    A Blog for the Curious Economist — and Everyone Else
    The Capital Question
    Marxist Political Economy Economic Policy 8 min read

    How Can Economic Policy Address Fixed-Capital Surpluses or Deficits Without Resorting to Paper Money?

    Starting from a problem outlined only embryonically by Marx in Volume II of Capital, this article examines how a post-capitalist society could address surpluses and deficits of fixed capital without resorting to paper money or, more generally, to monetary policy.

    MG
    José Mauricio Gómez Julián
    Contribuciones a la Economía • January 2016 • ISSN 1696-8360

    In contemporary economies, it is difficult to conceive of an economic policy intended to manage the surplus or deficit of a commodity without resorting, in one way or another, to monetary policy. The article begins from this observation and focuses the problem on a particularly important variable: fixed capital. Its objective is to demonstrate that, in a post-capitalist society, it would be possible to control surpluses and deficits of fixed capital without resorting to paper money or to variables associated with it.

    Introduction: The Problem and Its Scope

    The analysis constitutes a complementary theoretical development of a problem raised by Marx in Volume II of Capital. The article uses the same theoretical example as Marx, while noting that the phenomenon may originate from various causes that fall outside the scope of its analysis. Likewise, the imbalance need not occur exclusively between the major sectors of the economy: it can arise at both the intersectoral and intrasectoral levels.

    In a capitalist society, the consequences of these imbalances are not essentially different from those caused by the surplus — overproduction — or deficit — scarcity — of any other commodity. Foreign trade may provide a short-term outlet. In the case of a surplus, it can make it possible to transform into means of consumption part of the commodity of Sector I that has become immobilized in monetary form; in the case of a deficit, it can contribute to disposing of the remaining commodities associated with the amortization of fixed capital. But this solution does not eliminate the contradiction: it merely displaces it into a broader sphere, expanding its field of action and potentially the magnitude of its consequences.

    The central problem is not simply how much fixed capital exists, but how to maintain its proportionality with circulating capital when the physical replacement of the former varies from one year to another.

    The Two Theoretical Scenarios

    The reasoning is developed through the relationship between two sectors: the sector producing means of production and the sector producing means of consumption. The decisive question is how the relationship between the fixed and circulating components of constant capital changes when the proportion of fixed capital that must be physically replaced varies.

    1

    First Scenario

    If the portion of the production of means of production devoted to replacing the fixed capital of the sector producing means of consumption increases, while the total production intended to supply that sector with constant capital remains unchanged, the increase in amortization alters the proportion between the replacement of fixed capital and the circulating elements required. A larger portion of the fixed capital restored in monetary form flows toward the sector producing means of production in order to recover its natural form, so that more money circulates with the unilateral function of a means of purchase, while the mass of commodities exchanged between the two sectors changes.

    Outcome → SURPLUS IN FIXED-CAPITAL PRODUCTION
    2

    Second Scenario

    If the proportion of the fixed capital of the sector producing means of consumption that must be reproduced in kind — that is, physically replaced all at once — decreases, the portion that only needs to be replaced in money through the reserve fund increases correspondingly. The mass of circulating elements of constant capital reproduced by the sector producing means of production remains unchanged, while the production of fixed capital subject to replacement decreases.

    Outcome → DEFICIT IN FIXED-CAPITAL PRODUCTION

    The Economic Policy Proposal

    The article then takes its decisive step. Once the capitalist mode of production — and, with it, paper money in the terms of the argument being developed — has been abolished, the problem of proportionality between fixed and circulating capital is fundamentally reduced to the fact that the magnitude of fixed capital that is exhausted and must be physically replaced may vary from one year to another. These variations can offset one another successively, while, ceteris paribus, the remaining portion of constant capital required for the annual production of articles of consumption — raw materials, auxiliary materials, and intermediate materials — need not decrease.

    The answer proposed by the article is continuous relative overproduction: producing a certain quantity of fixed capital beyond immediate requirements and maintaining stocks of raw materials, auxiliary materials, and intermediate materials above annual needs.

    These surplus use-values would not be commodities produced without an outlet, but rather a reserve fund. Its function would be to provide the production process with whatever portion of constant capital is required at any given moment: fixed capital when there is a deficit in its fixed component, or circulating elements when the imbalance requires reinforcement of that component. The purpose is to prevent variations in the replacement of fixed capital from reducing or disrupting the reproduction of the system.

    In this way, the proposal does not consist in eliminating the material variations that give rise to the imbalances, but rather in consciously maintaining reserves capable of compensating for them. The year-to-year fluctuation in the physical replacement of fixed capital remains; what changes is the social mechanism through which society responds to it.

    Why the Same Policy Would Not Work Under Capitalism

    The article stresses that such a policy would have a completely different meaning within a capitalist society. There, it would constitute an element of anarchy because planning does not belong to the essence of the system. Moreover, capitalist overproduction is not “relative” in the specific sense employed by the proposal: it generates commercial crises. Nor does it take the form of continuous overproduction consciously maintained as a reserve; instead, commercial crises display a cyclical character.

    The fundamental difference therefore lies in the organization of the production process. In the post-capitalist framework proposed by the article, the surplus is deliberately produced as a reserve of use-values in order to guarantee reproduction; under capitalism, overproduction emerges within a system whose dynamics are not governed by such conscious planning and leads to commercial crises.

    • • •

    A Brief Final Assessment

    The article concludes by shifting attention from the technical problem to the history of Marxist theory. Gómez Julián points out that the Dictionary of Political Economy by Borisov, Zhamin, and Makarova — which he takes as a synthesis of Soviet economic theory of its time — neither develops nor even mentions this problem in its entries on “Fixed Capital,” “Simple Reproduction,” or “Expanded Reproduction.”

    This omission is particularly significant for the author because Marx had already posed the problem, although only in embryonic form, on pages 414–417 of Volume II of Capital. Gómez Julián regards the issue as vitally important both for Marxist theory and for the construction of a communist society or any other post-capitalist society.

    From this, he formulates a deliberately severe criticism of Soviet Marxism: he interprets the absence of this theoretical development as evidence that numerous foundations of the theory were not adequately understood either theoretically or practically, and he polemically connects that assessment with the historical outcome symbolized by November 9, 1989.

    The Article’s Thesis, in Summary

    The argument can be condensed as follows: year-to-year variations in the portion of fixed capital that must be physically replaced generate imbalances between fixed and circulating capital. Under capitalism, these imbalances manifest themselves within a commodity and monetary structure and may result in overproduction, scarcity, and crisis. In a post-capitalist society, by contrast, the article proposes dispensing with paper money in dealing with this problem through continuous relative overproduction of fixed capital and circulating elements, with the resulting surpluses accumulated as reserve funds and used according to the material requirements of reproduction.

    This post presents in accessible language the argument developed by José Mauricio Gómez Julián. The phenomenon analyzed may arise from various causes — which the article does not examine because of its chosen scope — and may occur at both the intersectoral and intrasectoral levels. For the original theoretical development and its direct connection with Marx, see: Gómez Julián, J. M. (2016), “¿Cómo realizar política económica ante superávit o déficit de capital fijo sin recurrir al papel moneda?”, Contribuciones a la Economía.
    Original Article Gómez Julián, José Mauricio. “¿Cómo realizar política económica ante superávit o déficit de capital fijo sin recurrir al papel moneda?” Contribuciones a la Economía, January 2016, ISSN 1696-8360.
    Full text: https://dialnet.unirioja.es/servlet/articulo?codigo=9041512

    Main references in the article: Karl Marx, Capital, Fondo de Cultura Económica, 2010; Borisov, Zhamin, and Makarova, Dictionary of Political Economy, 1965.

    The Capital Question — Political economy explained through its fundamental theoretical problems.